-
We detected your language preference as English. Would you like to switch to the English version for a better experience?
Switch to English
Stay here


Phosphorous acid (CAS 13598-36-2) is the phosphorus(III) oxyacid of formula H3PO3 and relative molecular mass 82.00, correctly represented as the tetrahedral phosphonic tautomer HP(O)(OH)2 rather than as a triprotic acid. It is supplied as a white, deliquescent crystalline solid melting near 73 °C, or as concentrated aqueous solution, and is distinguished from phosphoric acid by the direct phosphorus-hydrogen bond that gives the molecule pronounced reducing character. That single structural feature determines its handling profile, its reactivity and most of its industrial value.
Commercially, phosphorous acid is a high-tonnage inorganic intermediate rather than a specialty product. Its demand is pulled by four downstream systems: phosphite fungicides and phosphate-equivalent plant nutrition, organophosphonate scale and corrosion inhibitors for industrial water treatment, phosphite antioxidants and heat stabilisers for polymers, and metal-surface and electroless-plating chemistry. Each sector imposes a different impurity tolerance, so the commercial art lies in matching grade to application rather than in producing the molecule.
The economics are inseparable from the phosphorus value chain. Production cost tracks yellow phosphorus and phosphorus trichloride pricing, electric-arc furnace energy, hydrogen chloride by-product valorisation and freight, all of which shifted materially in recent years. Sections II to IX examine the acid-base and redox chemistry, the hydrolysis-based production technology, the application matrix, the supply-demand and pricing structure, the REACH, CLP, TSCA and EPA constraint set, the ESG profile of phosphorus processing, packaging and corrosive-goods logistics, and a practical expansion strategy for 2026.
Phosphorous acid is diprotic, not triprotic: two acidic protons are bound to oxygen while the third is bonded directly to phosphorus and is not ionisable. The first dissociation is strong and the second moderately weak, so solutions buffer across a wide working range. The phosphorus-hydrogen bond is the functional centre, rendering the molecule a reducing agent oxidised to phosphoric acid by air and other oxidants. Thermal behaviour is equally decisive, since strong heating disproportionates the acid to phosphoric acid with liberation of phosphine, a highly toxic gas.
Virtually all commercial phosphorous acid is made by controlled hydrolysis of phosphorus trichloride, a highly exothermic reaction that yields three equivalents of hydrogen chloride alongside the acid. Plant design is therefore defined by heat removal, hydrogen chloride capture and materials of construction rather than by the chemistry itself. Alternative routes based on dialkyl phosphite hydrolysis serve niche, high-purity requirements. Product quality is set downstream, in the concentration, crystallisation and chloride-polishing steps that separate technical from food-contact and electronic grades.
Three structural drivers now shape consumption. Agricultural demand has shifted toward phosphite-based plant-defence and nutrition products as growers seek tools compatible with resistance management and tightening fungicide approvals. Industrial water treatment is expanding because water-reuse targets, cooling demand from data centres and stricter discharge permits all favour high-performance phosphonate programmes. Polymer stabiliser demand tracks packaging and durable-goods output, while stewardship scrutiny of phosphorus discharge encourages formulation efficiency.
Capacity follows the phosphorus chain, and the phosphorus chain is concentrated where electric-arc furnace capacity and phosphate rock access coincide. China dominates integrated yellow phosphorus, phosphorus trichloride and phosphorous acid production, with capacity clustered in southwestern provinces where electricity cost and hydrology drive operating rates. North American and European capacity is generally captive or tied to downstream phosphonate and agrochemical formulation, and is exposed to energy-cost swings. Export flows therefore run from Asian producers to agrochemical formulators, water-treatment compounders and polymer-additive makers worldwide.
Phosphorous acid is priced as a commodity with grade-driven spreads. Technical grade follows yellow phosphorus, phosphorus trichloride and energy, with regional differentials created by electricity tariffs, environmental-compliance cost and freight. Low-chloride, low-arsenic and electronic grades command substantial premiums because the additional purification, analytical control and campaign scheduling carry real cost. Contract structures increasingly link price to an energy or feedstock index, and regulated buyers accept premium terms in exchange for documented impurity profiles and change-control commitments.
Phosphorous acid itself is regulated primarily as a corrosive industrial chemical, but its commercial fate is determined by the approvals governing its downstream uses. Registration, classification and transport obligations sit with the acid; plant-protection, biocidal, water-treatment and food-contact authorisations sit with the formulations and derivatives made from it. A supplier that understands only the first layer will repeatedly lose business to competitors who can support customers through the second. Documentation breadth across both layers is the practical barrier to entry in regulated segments.
Environmental scrutiny of phosphorus chemicals is structural rather than cyclical. Upstream electric-arc furnace production of elemental phosphorus is electricity-intensive, phosphorus is classified as a critical raw material in European policy, and phosphate discharge is a recognised eutrophication risk. Customers in agrochemical, water and polymer chains increasingly require Scope 1–3 emissions data, water-withdrawal reporting and product-stewardship documentation as a precondition of qualification, making environmental performance as commercially decisive as assay.
The cradle-to-gate footprint is dominated by Scope 2 electricity embedded in elemental phosphorus, followed by steam and vacuum energy for concentration and by furnace off-gas management. Decarbonisation therefore depends on low-carbon power at the phosphorus stage more than on downstream optimisation, although heat integration, vapour recompression and improved hydrogen-chloride recovery deliver real gains. Circular practice focuses on valorising the hydrogen chloride co-product, recovering phosphorus from wastewater and sewage-sludge ash, and recycling spent phosphite baths. Scope 3 reduction requires joint programmes with rock and energy suppliers.
Traceability begins with phosphate rock and elemental phosphorus provenance, since ore origin determines impurity load, natural radionuclide content and upstream emissions. Credible producers operate qualified-supplier programmes with audit, change-control notification before any site or route change, and retention sampling for retrospective investigation. ISO 9001 provides the management-system baseline and ISO 14001 the environmental baseline, increasingly complemented by energy-management systems. Water stewardship deserves particular attention: phosphorus discharge limits are tightening in most jurisdictions, so effluent performance and documented mass balance now form part of the supplier proposition.
Logistics for phosphorous acid are governed by two properties: extreme hygroscopicity and corrosivity. Material that absorbs moisture cakes, loses assay consistency and attacks unsuitable packaging, while leaks in transit create both safety and liability exposure. Resilience planning therefore emphasises packaging qualification, regional stocking to shorten lead times, and carrier selection based on demonstrated dangerous-goods competence rather than on rate alone. Buyers should also confirm that suppliers hold adequate safety stock of phosphorus trichloride, since upstream outages propagate quickly.
Phosphorous acid is consigned as a Class 8 corrosive, with solid material shipped under its dedicated UN corrosive-solid entry and aqueous grades assessed against the applicable corrosive-liquid entry. Sea, road and rail movements follow IMDG, ADR and national dangerous-goods rules, with documented segregation, spill containment and emergency-response information carried on board. Because the substance is hygroscopic and corrosive, container selection and dunnage matter as much as classification. Customs declarations must state the correct CAS number and inorganic-acid tariff heading, since misclassification of phosphorus acids causes recurring clearance delay.
Commodity position does not preclude differentiation. The participants that sustain margin in phosphorus oxyacids do so by coupling cost-efficient production with specification breadth and downstream regulatory support.
Phosphorous acid is a deceptively simple molecule whose commercial performance depends on discipline rather than novelty. Diprotic acidity, P(III) reducing behaviour, thermal disproportionation to phosphine and extreme hygroscopicity define the handling envelope, while chloride, arsenic and heavy-metal control define the addressable market. Producers that master the hydrolysis-hydrogen-chloride system and invest in purification can serve agrochemical, water-treatment, polymer and metal-treatment customers from a single asset base.
The outlook favours suppliers who integrate environmental performance into their offer. Phosphorus is a critical raw material, its upstream production is electricity-intensive, and discharge limits are tightening, so Scope 1–3 emissions data, water stewardship and hydrogen-chloride valorisation will increasingly determine qualification outcomes. Buyers should specify grade and impurity limits explicitly, index contracts to transparent feedstock benchmarks, qualify packaging against real lane conditions, and treat change-control commitments as a core term rather than a courtesy.
Powered by Guidechem
This white paper is exclusively compiled by the Guidechem Intelligence Team based on global customs data, regulatory databases, and industry research. Guidechem is a leading global B2B chemical platform, dedicated to connecting global buyers with verified, high-quality manufacturers.
Relying on Guidechem's extensive global database, we have mapped the core participants in the current global Phosphorous acid supply chain:
Disclaimer: The content of this white paper is compiled based on public market data and regulatory information available as of 2026. Global chemical regulations are subject to dynamic adjustments. In actual export operations, enterprises must consult professional regulatory advisors or relevant competent authorities to obtain the latest compliance guidance.
|
 |
 |
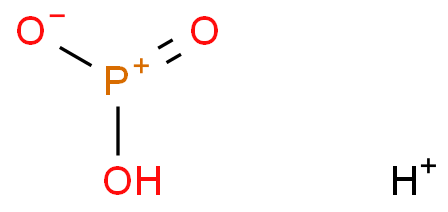 |
 |
 |
 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 1YR

