Daily Chemical Market Price Overview — October 9, 2026
The second post-holiday session carried the rally decisively into the broad market.
45 of 134 tracked products moved, 31 higher and 14 lower, and unlike yesterday the gains were overwhelmingly genuine rather than reference resets.
Mineral oil shows the largest nominal figure at +81.82% to CNY 72,000/ton, which is a data-artefact explained in the cards below, but the real story is one level down:
ethyl acetate fell 10.17% to CNY 6,324/ton,
Trichloroethylene rose 5.44% to CNY 4,613/ton,
Formic acid gained 5.00% to CNY 2,100/ton,
Anthracite recovered 4.76% to CNY 1,650/ton and
Acetone jumped 4.41% to CNY 8,738/ton. The upstream complex was the engine:
WTI Crude Oil rose 3.41% to USD 91/barrel in the tracked basket,
Propylene added 3.14% to CNY 10,291/ton,
Dichloromethane 3.08% to CNY 2,778/ton,
Propylene glycol 3.85% to CNY 9,150/ton,
Hydrochloric acid 3.72% to CNY 195/ton and
Formaldehyde 2.76% to CNY 1,863/ton. On the downside,
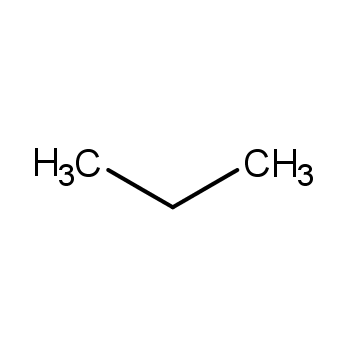
Propane lost 5.69% to CNY 5,800/ton,
Glycerol 3.06% to CNY 9,500/ton and
Ethylene glycol 2.46% to CNY 6,267/ton.
Three conditions set the tone. First, crude delivered the cost shock that the chemical chain had been waiting for: after President Trump said publicly that the United States would not attack Iran before the November 3 midterm elections and Tehran confirmed indirect talks were continuing through mediators, the risk premium did not fade but hardened, with November WTI settling USD 3.21 higher at USD 91.49, up 3.64%, and December Brent up USD 4.08 at USD 104.28, up 4.07%, as a new United States sanctions round targeting Iranian crude shipping and fresh strikes on tankers in Hormuz combined with hurricane-driven Gulf of Mexico shut-ins. Second, methanol extended its squeeze, with the Zhengzhou main contract rising as much as 10% intraday to CNY 3,925 before closing 7.48% higher, after port inventory fell a further 22.47% to 305,100 tonnes — an all-time low and only 23,500 tonnes of visible foreign arrivals during the period. Third, the basket was refilled: 31 lines returned to tracking and four were retired, so week-on-week comparisons across that gap remain unreliable and every re-based level is flagged explicitly below.

Top Price Movers
Mineral oil shows the largest nominal move in the dataset, rising 81.82% to CNY 72,000/ton from CNY 39,600/ton.
This is an accounting artefact, not a price move. The product re-entered the basket on October 9 after being absent on October 8, and its October 8 re-entry level of CNY 39,600/ton is the only reading in this series that has ever departed from CNY 72,000/ton — the identical figure carried on September 22, 23 and 29. The weekly change of minus 9.39% and the monthly change of minus 18.83% are both inconsistent with an 81.82% advance and confirm that CNY 39,600/ton was the anomaly. Readers should treat
CNY 72,000/ton as the standing reference and disregard the percentage. Mineral oil covers white oils and technical process oils sold into cosmetics, pharmaceutical, food-processing and polymer applications, and no supply event remotely of this scale has been reported in any of those markets.
Heads-up — the 81.82% print is not a market move: mineral oil simply returned to its long-standing CNY 72,000/ton reference after one anomalous reading of CNY 39,600/ton on October 8.
Ethyl acetate fell 10.17% to CNY 6,324/ton, the largest genuine decline of the session and a notable one because it runs directly against the rest of the acetate chain. The product is 4.40% higher on the week and 8.15% higher on the month, which suggests the drop is at least partly a reference correction from yesterday's rebound, but there is a real divergence underneath. Industry assessments moved the other way on October 9: East China ex-works quotes were raised CNY 250/tonne to around CNY 7,010/tonne and North China by CNY 120/tonne to CNY 6,770/tonne, on higher acetic acid and ethanol costs, with the sector-wide benchmark up 0.33% to CNY 7,063.33/tonne and the one-year position assessed as mid-to-high. The explanation is likely grade and delivery-basis mismatch rather than a genuine collapse, and buyers should
verify the quoted basis before treating CNY 6,324/ton as achievable. Ethyl acetate demand is concentrated in coatings, adhesives, printing inks, extraction and flavour and fragrance, and Q4 coatings demand in China typically softens after the October peak.
Price dropped 10.17% today — the sharpest real decline of the session, but note it conflicts with East China and North China producer increases of CNY 250/tonne and CNY 120/tonne on the same day. Check the delivery basis.
Propane fell 5.69% to CNY 5,800/ton, effectively retracing the level it held on October 8 before the basket refresh. The product is 0.96% lower on the week and 2.50% lower on the month, so this is a genuine softening rather than a reset, and it sits in contrast to the rest of the LPG complex. International pricing was firm — Saudi Aramco's September contract price was set at USD 625/tonne for propane, USD 5/tonne higher month on month, equivalent to an arrived cost of roughly CNY 6,239/tonne, and reported East China import cargoes were assessed at CNY 8,009/tonne, up CNY 115/tonne, with Lianyungang imported propane at CNY 8,060/tonne. Domestic fundamentals are looser: Chinese LPG sample producer volumes rose 0.19% to 482,100 tonnes, the producer-to-sale ratio held at 100%, storage capacity utilisation edged up to 18.63% and port inventory climbed 1.08% to 2.1456 million tonnes. The tracked figure of CNY 5,800/ton is well below the import parity level, which points to a domestic or regional assessment rather than a benchmark.
Price dropped 5.69% today — domestic propane is trading at a deep discount to import parity of roughly CNY 6,239/tonne; worth checking against landed-cost economics before locking in supply.
Basic Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
4,860 |
0% |
0.66% |
17.68% |
| Acetic anhydride prices |
108-24-7 |
7,190 |
0% |
0.1% |
9.44% |
| Acetone prices |
67-64-1 |
8,738 |
4.41% |
-0.68% |
0.07% |
| Acetonitrile prices |
75-05-8 |
8,625 |
0% |
5.36% |
4.14% |
| Ammonium chloride prices |
12125-02-9 |
867 |
0% |
0.13% |
-6.25% |
| Ammonium nitrate prices |
6484-52-2 |
4,150 |
0% |
0% |
0% |
| Ammonium sulfate prices |
7783-20-2 |
1,293 |
-0.54% |
-0.76% |
7.12% |
| Aniline prices |
62-53-3 |
15,200 |
2.01% |
0.99% |
8% |
| Benzene prices |
71-43-2 |
10,501 |
0.8% |
1.38% |
7.93% |
| Benzoic acid prices |
65-85-0 |
9,100 |
0% |
3.41% |
8.29% |
| Borax prices |
1303-96-4 |
6,640 |
1.84% |
0.46% |
3.47% |
| boric acid prices |
10043-35-3 |
11,600 |
0% |
0% |
0.47% |
| calcium carbide prices |
75-20-7 |
2,580 |
0% |
-1.97% |
2.38% |
| Calcium phosphate prices |
7758-87-4 |
10,000 |
0% |
0% |
0% |
| Caustic Soda prices |
68988-74-9 |
633 |
-0.31% |
-0.16% |
-0.47% |
| Chloroform prices |
67-66-3 |
2,417 |
0% |
0% |
6.52% |
| Cobalt prices |
7440-48-4 |
262,700 |
-0.08% |
-0.16% |
-7.82% |
| Copper sulfate prices |
7758-98-7 |
25,767 |
0.52% |
1.94% |
-14.89% |
| Dichloromethane prices |
75-09-2 |
2,778 |
3.08% |
-2.3% |
18.05% |
| distilled water prices |
- |
450 |
0% |
0% |
0% |
| Ethanol prices |
64-17-5 |
5,632 |
0.46% |
0.11% |
0.92% |
| ethyl acetate prices |
141-78-6 |
6,324 |
-10.17% |
4.4% |
8.15% |
| Ethylene prices |
74-85-1 |
8,500 |
0% |
0% |
0% |
| Ethylene glycol prices |
107-21-1 |
6,267 |
-2.46% |
-1.07% |
-1.95% |
| Ethylene Oxide prices |
75-21-8 |
9,700 |
0% |
0% |
7.93% |
| EVA prices |
- |
11,033 |
0% |
0% |
2.32% |
| Formaldehyde prices |
50-00-0 |
1,863 |
2.76% |
1.64% |
6.54% |
| Formic acid prices |
64-18-6 |
2,100 |
5% |
0.3% |
-11.1% |
| Glycerol prices |
56-81-5 |
9,500 |
-3.06% |
-0.52% |
-0.99% |
| Heptane prices |
142-82-5 |
16,200 |
0.62% |
0.12% |
3.47% |
| Hexane prices |
110-54-3 |
10,325 |
0% |
0% |
5.43% |
| Hydrochloric acid prices |
7647-01-0 |
195 |
3.72% |
1.07% |
3.28% |
| Hydrogen peroxide prices |
7722-84-1 |
713 |
0% |
-0.14% |
3.18% |
| Iodine prices |
7553-56-2 |
640 |
0% |
0% |
0% |
| Kaolin prices |
1332-58-7 |
850 |
0% |
0% |
0% |
| Lithium carbonate prices |
554-13-2 |
121,000 |
-1.63% |
0.07% |
-11.31% |
| Magnesium chloride prices |
7786-30-3 |
880 |
0% |
0% |
0% |
| Magnesium oxide prices |
1309-48-4 |
1,300 |
0% |
0% |
0% |
| Magnesium sulfate prices |
7487-88-9 |
1,000 |
0% |
0% |
0% |
| Methanol prices |
67-56-1 |
4,847 |
2.41% |
2.1% |
17.5% |
| Mineral oil prices |
8042-47-5 |
72,000 |
81.82% |
-9.39% |
-18.83% |
| Nickel prices |
7440-02-0 |
121,867 |
-0.3% |
-0.91% |
-2.86% |
| Paraffin wax prices |
8002-74-2 |
9,800 |
0% |
0% |
0% |
| PET prices |
- |
9,044 |
1.14% |
1.19% |
2.9% |
| Phenol prices |
108-95-2 |
9,355 |
2.46% |
1.73% |
1.52% |
| Phosphoric Acid prices |
7664-38-2 |
8,375 |
0% |
0.05% |
-0.21% |
| Poly(vinyl alcohol) prices |
9002-89-5 |
10,400 |
0% |
0% |
0% |
| Potassium carbonate prices |
584-08-7 |
7,450 |
0% |
-0.09% |
-0.63% |
| Potassium chloride prices |
7447-40-7 |
3,333 |
0% |
-0.21% |
0.06% |
| Propane prices |
74-98-6 |
5,800 |
-5.69% |
-0.96% |
-2.5% |
| Propylene prices |
115-07-1 |
10,291 |
3.14% |
1.78% |
2.09% |
| Propylene glycol prices |
57-55-6 |
9,150 |
3.85% |
-0.47% |
-0.31% |
| PX prices |
- |
9,900 |
0% |
0.14% |
4.46% |
| Pyridine prices |
110-86-1 |
18,471 |
0% |
0% |
0.18% |
| Silicon prices |
7440-21-3 |
9,600 |
0.52% |
0.26% |
0.68% |
| Sodium bicarbonate prices |
144-55-8 |
1,200 |
0% |
0% |
-0.25% |
| Sodium carbonate prices |
497-19-8 |
1,260 |
0% |
0% |
0% |
| Sodium chloride prices |
7647-14-5 |
500 |
0% |
0% |
0% |
| Sodium fluoride prices |
7681-49-4 |
4,150 |
0% |
-0.92% |
-1.49% |
| Sodium hydroxide prices |
1310-73-2 |
2,567 |
0% |
0% |
1.1% |
| Sodium sulfate prices |
7757-82-6 |
560 |
0% |
0% |
0% |
| Sulfur prices |
7704-34-9 |
7,392 |
-0.14% |
-1.71% |
-4.85% |
| Sulfur hexafluoride prices |
2551-62-4 |
28,100 |
0% |
0% |
0% |
| sulfuric acid prices |
7664-93-9 |
1,678 |
-1.87% |
-0.58% |
-4.69% |
| Titanium dioxide prices |
13463-67-7 |
14,220 |
0% |
0% |
0.44% |
| Toluene prices |
108-88-3 |
8,883 |
2.02% |
0.76% |
5.7% |
| Urea prices |
57-13-6 |
1,768 |
-0.56% |
-0.22% |
0.4% |
| White cement prices |
- |
450 |
0% |
0% |
0% |
| White phosphorus prices |
12185-10-3 |
27,800 |
0.12% |
0% |
-0.25% |
| Xylene prices |
1330-20-7 |
8,703 |
2.15% |
0.56% |
1.17% |
| Zinc chloride prices |
7646-85-7 |
11,825 |
0% |
0% |
0% |
Basic chemicals saw
33 of 71 tracked products move, 25 higher and 8 lower, by far the most one-sided positive balance this series has recorded. Setting aside the mineral-oil artefact, the strongest gains were
Formic acid up 5.00% to CNY 2,100/ton,
Acetone up 4.41% to CNY 8,738/ton,
Propylene glycol up 3.85% to CNY 9,150/ton,
Hydrochloric acid up 3.72% to CNY 195/ton,
Propylene up 3.14% to CNY 10,291/ton,
Dichloromethane up 3.08% to CNY 2,778/ton,
Formaldehyde up 2.76% to CNY 1,863/ton,
Phenol up 2.46% to CNY 9,355/ton,
Methanol up 2.39% to CNY 4,847/ton and
Acetic acid up 0.35% to CNY 4,860/ton.
Gasoline added 0.91% to CNY 10,111/ton and
PET rose 1.14% to CNY 8,942/ton. Declines were limited to
Propane down 5.69% to CNY 5,800/ton,
Glycerol down 3.06% to CNY 9,500/ton,
Ethylene glycol down 2.46% to CNY 6,267/ton and
Lithium carbonate down 1.63% to CNY 121,000/ton.
Methanol remained the centre of gravity. Spot added 2.39% to CNY 4,847/ton and now stands 118.69% above the year-earlier level, while the Zhengzhou main contract surged as much as 10% intraday to CNY 3,925/ton before settling 7.48% higher — the widest single-session move of any contract in the market. The physical squeeze has tightened again:
port inventory fell 22.47% over the period to 305,100 tonnes, an all-time low, with only 23,500 tonnes of visible foreign cargo discharged, and East China destocked 79,900 tonnes and South China 8,500 tonnes. The path has been relentless — 412,000 tonnes on September 23, roughly 393,500 tonnes in East China by September 30, then 305,100 tonnes after the holiday. Iranian plants remain largely shut, unable to restart on shipping and gas constraints, and winter gas curtailment looms. Industry analysts expect further destocking over the next five weeks, while flagging the two-way risk: domestic operating rates had already recovered above 91% before the holiday, MTO margins are deeply negative with several coastal plants idled, and any sign of Hormuz reopening would release Iranian floating storage. The structure is emphatically
"strong nearby, weak deferred".
The propylene chain delivered the broadest gains, which is exactly what a crude shock should produce.
Propylene rose 3.14% to CNY 10,291/ton with a 6.01% weekly gain and a 56.20% annual gain, supported by the withdrawal of several northern PDH units for planned maintenance and by Shandong assessments rising CNY 335/tonne in a single session.
Acetone jumped 4.41% to CNY 8,738/ton, confirmed by Jiangsu assessments up CNY 125/tonne to CNY 8,650/tonne from cost-push and firm seller discipline, with the annual comparison now 97.92%.
Phenol gained 2.46% to CNY 9,355/ton and
Propylene glycol rose 3.85% to CNY 9,150/ton, the latter reversing most of yesterday's decline as industrial-grade propylene glycol firmed 0.69% to CNY 9,766.67/tonne.
Formaldehyde added 2.76% to CNY 1,863/ton and the broader formaldehyde market ran even harder, with national averages up CNY 140/tonne or 7.71% on methanol cost pass-through, though producers are reporting thin follow-through from a downstream that is resisting the higher numbers.
Formic acid gained 5.00% to CNY 2,100/ton, the largest genuine advance in the segment, on a combination of low social inventory, reduced availability as some units took maintenance and firm rigid demand from leather, textile dyeing, feed and rubber applications — although the product remains 28.41% below its year-earlier level.
Chlor-alkali and the aromatics both firmed.
Hydrochloric acid rose 3.72% to CNY 195/ton, extending the annual gain to 129.41%, as producers lifted offers into firm demand from water treatment, steel pickling and calcium chloride production.
Dichloromethane added 3.08% to CNY 2,778/ton, a second consecutive daily advance that follows the round of Shandong producer increases on October 8 and leaves the product 18.05% higher on the month and 74.34% higher on the year, though the one-year price position is in the top band, which caps further upside. On the aromatics side, the segment-wide benchmark rose 0.80% to CNY 10,501/tonne for benzene, with toluene up 2.03% to CNY 8,883.33/tonne and mixed xylenes up 2.15% to CNY 8,703.33/tonne.
Acetic acid edged 0.35% higher to CNY 4,860/ton, holding an 84.09% annual gain on the ongoing turnaround season, and
Acetic anhydride at CNY 7,190/tonne remains 70.68% higher year on year.
PET rose 1.14% to CNY 8,942/ton, consistent with bottle-grade assessments up 3.37% to CNY 9,050/tonne as PTA jumped 6.74% in spot terms on the crude move.
The declines were confined to the glycol, glycerol and lithium chains and are worth reading as a group.
Ethylene glycol fell 2.46% to CNY 6,267/ton and was one of the worst performers on the domestic futures market, down 4.16%, because the supply side is loose where everything else is tight:
East China main-port inventory rose 15,000 tonnes to 101,000 tonnes, a 17.44% increase, capacity utilisation stands at 64.51%, and the polyester chain operates at 72.75% with filament sales ratios collapsing from 289.80% to 24.60% after the holiday stocking burst. Expectations of continued loose domestic supply make the near-term direction lower, with East China spot self-pickup assessed at CNY 6,100–6,200/ton.
Lithium carbonate fell 1.63% to CNY 121,000/ton, tracking a 3.74% drop in the futures contract as the post-holiday restocking impulse faded, although the battery-grade benchmark still shows a 65.26% annual gain and both battery-grade lithium hydroxide and industrial-grade material retreated in parallel.
Propane and
Glycerol are discussed above. Meanwhile
Copper sulfate and
Sodium dodecyl sulfate both held flat at CNY 25,767/ton and CNY 14,850/ton respectively, confirming that yesterday's corrections have settled.
A large number of high-volume basics were unchanged.
Ethylene Oxide held at CNY 9,700/ton with a 53.97% annual gain,
Aniline at CNY 14,900/tonne with a 92.26% annual gain,
Epichlorohydrin at CNY 11,200/ton,
Titanium dioxide at CNY 14,220/ton with a 2.60% annual gain,
White phosphorus at CNY 27,766/ton,
EVA at CNY 11,033/ton,
sulfuric acid at CNY 1,710/ton,
soda ash at CNY 1,050/ton,
Caustic soda at CNY 635/ton,
Ethanol at CNY 5,606/ton,
phosphoric acid at CNY 8,375/ton,
Ammonium sulfate at CNY 1,300/ton and
calcium carbide at CNY 2,580/ton. The most important of these is
calcium carbide, which held after yesterday's 6.18% decline and was confirmed flat at the industry benchmark level of CNY 2,580/tonne with the annual comparison still positive at 0.86%, suggesting the carbide correction has found a floor even as PVC producers remain loss-making.
Sulfur eased only 0.14% to CNY 7,392/ton after yesterday's 3.90% drop. Overall, Basic Chemicals has moved into a
clear cost-push regime driven by methanol and crude, with the exceptions being the glycol and lithium chains where supply is structurally long.
Fine Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Activated carbon prices |
64365-11-3 |
4,200 |
0% |
0% |
0% |
| antifreeze prices |
- |
800 |
0% |
0% |
0% |
| azelaic acid prices |
123-99-9 |
80,000 |
0% |
0% |
0% |
| Benzyl alcohol prices |
100-51-6 |
18,500 |
0% |
0% |
0.45% |
| Castor oil prices |
8001-79-4 |
14,500 |
0% |
0% |
1.3% |
| chlorine tablets prices |
- |
8,500 |
0% |
0% |
0% |
| Citric acid prices |
77-92-9 |
6,200 |
0% |
0% |
0% |
| Cocamidopropyl betaine prices |
61789-40-0 |
6,000 |
0% |
0% |
0% |
| Creatine monohydrate prices |
6020-87-7 |
20,980 |
0% |
-0.14% |
-0.14% |
| Cyanuric acid prices |
108-80-5 |
7,650 |
0% |
0.89% |
4.73% |
| dimethyl carbonate prices |
616-38-6 |
6,167 |
0% |
-0.05% |
-4.02% |
| Dimethyl sulfoxide prices |
67-68-5 |
10,850 |
0% |
0.34% |
4.03% |
| Ferric chloride prices |
7705-08-0 |
2,808 |
0% |
0% |
0.07% |
| glycolic acid prices |
79-14-1 |
13,000 |
0% |
0% |
0% |
| Guar gum prices |
9000-30-0 |
15,500 |
0% |
0% |
0% |
| Hydroquinone prices |
123-31-9 |
30,500 |
0% |
0% |
0% |
| Imidazole prices |
288-32-4 |
21,750 |
0% |
-0.05% |
0.59% |
| Lactic acid prices |
50-21-5 |
8,163 |
0% |
0% |
0.55% |
| Lauric acid prices |
143-07-7 |
18,500 |
0% |
0% |
-0.1% |
| Magnesium glycinate prices |
14783-68-7 |
29,000 |
0% |
0% |
0% |
| Mannitol prices |
87-78-5 |
18,000 |
0% |
0% |
0% |
| Melamine prices |
108-78-1 |
6,325 |
0% |
0.06% |
1.1% |
| Melatonin prices |
73-31-4 |
850 |
0% |
0% |
0% |
| Oleic acid prices |
112-80-1 |
10,000 |
0% |
0% |
0% |
| Palladium prices |
7440-05-3 |
11,500 |
0% |
0% |
0% |
| Petroleum prices |
8009-03-8 |
9,300 |
0% |
0% |
0% |
| Potassium Citrate prices |
866-84-2 |
8,750 |
1.74% |
0.87% |
-0.89% |
| Potassium iodide prices |
7681-11-0 |
45,000 |
0% |
0% |
0% |
| Potassium sorbate prices |
24634-61-5 |
15,100 |
0% |
0.78% |
9.95% |
| Quartz prices |
14808-60-7 |
6,800 |
0% |
0% |
0% |
| Silver iodide prices |
7783-96-2 |
1,804 |
0% |
0% |
15.42% |
| sodium acetate prices |
127-09-3 |
5,643 |
2.6% |
0.62% |
0.73% |
| Sodium alginate prices |
9005-38-3 |
130,000 |
0% |
0% |
0% |
| Sodium benzoate prices |
532-32-1 |
850 |
0% |
0% |
0% |
| Sodium dodecyl sulfate prices |
151-21-3 |
14,850 |
0% |
11.65% |
-4.02% |
| Sodium hypochlorite prices |
7681-52-9 |
553 |
0% |
0% |
0% |
| Sodium metabisulfite prices |
7681-57-4 |
3,903 |
0% |
-0.1% |
-1.01% |
| Sodium polyacrylate prices |
9003-04-7 |
18,000 |
0% |
0% |
0% |
| Stearic acid prices |
57-11-4 |
28,000 |
0% |
0% |
0% |
| Strontium oxide prices |
1314-11-0 |
8,500 |
0% |
0% |
0% |
| Tetrahydrofuran prices |
24979-97-3 |
19,000 |
-2.56% |
5.54% |
13.38% |
| tranexamic acid prices |
1197-18-8 |
330 |
0% |
0% |
0% |
| Trichloroacetic acid prices |
76-03-9 |
40,000 |
0% |
0% |
0% |
| Trichloroethylene prices |
79-01-6 |
4,613 |
5.44% |
-1.23% |
8.22% |
| Triclopyr prices |
55335-06-3 |
47,500 |
0% |
0% |
0% |
| Water softener salt prices |
- |
967 |
0% |
0% |
0% |
| Xanthan gum prices |
11138-66-2 |
21,000 |
0% |
0% |
0% |
Fine Chemicals were again the quietest segment but for once the moves were genuine rather than reference events. Only
4 of 47 products moved, 3 higher and 1 lower.
Trichloroethylene rose 5.44% to CNY 4,613/ton, a second consecutive daily advance that recovers most of the ground lost on September 29 and leaves the product 8.22% higher on the month despite a 1.23% weekly decline.
Sodium acetate added 2.60% to CNY 5,643/ton with a 0.62% weekly gain,
Potassium Citrate rose 1.74% to CNY 8,750/ton with a 0.87% weekly gain, and
Tetrahydrofuran fell 2.56% to CNY 19,000/ton — the sole decliner, but a level that is 5.54% higher on the week and 13.38% higher on the month, marking a clear upward re-rating from the CNY 17,000–17,250/ton band the product occupied through late September. The three lines added back to tracking this edition —
Palladium,
Silver iodide and
Strontium oxide — along with returning specialities such as
azelaic acid,
Benzyl alcohol,
Lauric acid and
Sodium alginate, all opened flat, so their first readings should be treated as indicative only.
The correction stories that dominated yesterday have now fully settled.
Cyanuric acid held at CNY 7,650/ton and is now 0.89% higher on the week and 4.73% higher on the month, confirming that the October 8 decline was the reference normalising rather than the start of a downtrend; actual Chinese 98.5% offers still cluster between CNY 5,100 and CNY 8,500/tonne, so the tracked level sits at the top of the real range.
Potassium sorbate held at CNY 15,100/ton with weekly and monthly gains of 11.73% and 16.28%, and
Dimethyl sulfoxide held at CNY 10,850/ton with weekly and monthly gains of 2.08% and 5.18%.
dimethyl carbonate was unchanged at CNY 6,167/ton, but the underlying market is tightening again: industry-grade material was raised to CNY 5,600/tonne, up CNY 260/tonne or 4.87%, on the strength of the methanol feedstock rally, and further increases are expected.
Melamine held at CNY 6,325/ton with a 13.96% annual gain, supported by firm urea and coal costs but capped by modest laminate and resin demand.
Everything else in the segment was untouched.
Citric acid held at CNY 6,200/ton,
Lactic acid at CNY 8,163/ton,
Hydroquinone at CNY 30,500/ton,
Oleic acid at CNY 10,000/ton,
glycolic acid at CNY 13,000/ton,
Ferric chloride at CNY 2,808/ton,
Sodium hypochlorite at CNY 553/ton,
Water softener salt at CNY 967/ton,
Mannitol at CNY 18,000/ton,
Stearic acid at CNY 28,000/ton,
Sodium polyacrylate at CNY 18,000/ton,
Xanthan gum at CNY 21,000/ton,
Guar gum at CNY 15,500/ton,
Castor oil at CNY 14,500/ton,
Quartz at CNY 6,800/ton,
Cocamidopropyl betaine at CNY 6,000/ton,
Activated carbon at CNY 4,200/ton and
Melatonin at CNY 850/kg.
Magnesium glycinate at CNY 29,000/ton,
Creatine monohydrate at CNY 20,980/ton,
Imidazole at CNY 21,750/ton and
Sodium metabisulfite at CNY 3,910/ton were likewise flat. Three lines left the basket this edition —
calcium chloride,
ferrous sulfate and
Retinol.
The practical read for fine chemicals buyers is that
this segment has now normalised. After two sessions in which the headline numbers were driven by reference resets, October 9 produced four small, credible moves and 43 unchanged lines. The one product where timing matters is
dimethyl carbonate, unchanged in the tracked table but firming hard in the spot market on methanol cost pass-through; the one where a trend has genuinely reversed is
Tetrahydrofuran, which has re-rated 13.38% higher over the month. For the rest, contract pricing is holding and there is no urgency to move.
Energy, Rubber, Plastic and other chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| ABS prices |
- |
11,733 |
1.88% |
1.36% |
1.25% |
| anaerobic bacteria prices |
- |
50 |
0% |
0% |
0% |
| Anthracite prices |
8029-10-5 |
1,650 |
4.76% |
-0.58% |
1.48% |
| Asphalt prices |
8052-42-4 |
6,265 |
-0.71% |
0.25% |
8.26% |
| Basalt prices |
- |
650 |
0% |
0% |
0% |
| Carbon prices |
7440-44-0 |
12,500 |
0.26% |
0.1% |
0.6% |
| Carbon Black prices |
1333-86-4 |
11,693 |
0% |
-0.12% |
3.18% |
| EAA prices |
- |
57,800 |
0% |
0% |
-0.81% |
| Gasoline prices |
- |
10,111 |
0.91% |
-0.98% |
1.8% |
| HDPE prices |
- |
10,663 |
1.67% |
0.14% |
-2.85% |
| kerosene prices |
- |
8,200 |
0% |
0% |
-0.11% |
| POE prices |
68441-17-8 |
16,500 |
0% |
0% |
0.24% |
| Poly(vinyl acetate) prices |
9003-20-7 |
12 |
0% |
0% |
0% |
| PVC prices |
- |
4,870 |
1.46% |
1.59% |
0.82% |
| Silica prices |
10279-57-9 |
6,400 |
0% |
0% |
2.88% |
| WTI Crude Oil prices |
- |
91 |
3.41% |
-2.2% |
-5.26% |
Energy, Rubber, Plastic and other chemicals saw
10 of 16 products move, 8 higher and 2 lower, and the segment produced the cleanest expression of the session's theme.
Anthracite recovered 4.76% to CNY 1,650/ton,
WTI Crude Oil rose 3.41% to USD 91/barrel,
ABS gained 1.88% to CNY 11,733/ton,
HDPE added 1.67% to CNY 10,663/ton,
PVC rose 1.46% to CNY 4,870/ton,
Gasoline added 0.91% to CNY 10,111/ton and
Carbon edged up 0.26% to CNY 12,500/ton, while
Asphalt eased 0.71% to CNY 6,265/ton.
Carbon Black at CNY 11,693/ton,
Silica at CNY 6,400/ton,
kerosene at CNY 8,200/ton,
EAA at CNY 57,800/ton,
POE at CNY 16,500/ton,
Poly(vinyl acetate) at CNY 12/kg,
Basalt at CNY 650/ton and
anaerobic bacteria at CNY 50/kg were all unchanged.
WTI Crude Oil was marked at USD 91/barrel, up 3.41%, against a settlement of USD 91.49 on October 8 — a USD 3.21 or 3.64% advance — with December Brent up USD 4.08 or 4.07% to USD 104.28. The catalyst was not a fading of risk but a re-pricing of it. President Trump stated publicly that the United States would not strike Iran before the November 3 midterm elections and described ongoing consultations as productive, and Iran's foreign minister confirmed indirect talks were continuing through mediators; yet the same day brought a fresh United States sanctions round covering vessels carrying Iranian crude, further tanker attacks in the Strait of Hormuz, and hurricane-driven shut-ins of Gulf of Mexico offshore production. Industry analysts see Brent holding a USD 102–106 range on the upside case and USD 89–93 for WTI, with the key dates being the October 10 CFTC positioning report and the October 14 EIA production assessment.
Gasoline added 0.91% to CNY 10,111/ton, keeping weekly loss to 0.98% and the monthly gain at 1.80%, consistent with firm energy-sector equities and the 2.47% rise in MTBE to CNY 8,300/tonne.
The plastic chain delivered a broad, cost-driven advance.
ABS rose 1.88% to CNY 11,733/ton, in line with the 1.88% move in Yuyao ABS 0215A to CNY 11,733.33/tonne, and now shows weekly and monthly gains of 1.36% and 1.25% with a 19.12% annual advance; styrene was flat at CNY 11,520/tonne after Tuesday's 8.58% spike, so the cost impulse is holding rather than building.
HDPE added 1.67% to CNY 10,663/ton, matching the segment benchmark's move to CNY 10,662.50/tonne and a 35.40% annual gain.
PVC rose 1.46% to CNY 4,870/ton, within reach of the CNY 4,880/tonne benchmark and with a 1.59% weekly gain; supply remains low with upstream operating rates around 64%, and although carbide costs continue to fall, ethylene-based producers are deeply loss-making on the crude move, so the floor is holding. Notably the whole plastics complex was up on the day — LDPE 2.47%, LLDPE 2.09%, polypropylene raffia 1.77%, PC 1.36% and PET 1.14% — a uniformity that points squarely to cost pass-through rather than product-specific demand.
Anthracite recovered 4.76% to CNY 1,650/ton, unwinding most of Thursday's anomalous 10.00% fall and returning to the level held through early October, with weekly and monthly changes of minus 0.58% and plus 1.48% confirming the coal complex is range-bound rather than trending.
Overall, the Energy, Rubber, Plastic and other chemicals segment confirms that
this is a cost-push rally with a geopolitical trigger, not a demand-led recovery. Crude, naphtha at CNY 9,678/tonne after a single-day 3.36% rise, propylene, methanol and PTA are all transmitting upward through the chain, and the polymers, aromatics and acetate derivatives are following. The counterweights are equally clear: carbide and coking coal are falling, ethylene is down 2.67% to CNY 9,100/tonne in outright contradiction of the rest of the complex, ethylene glycol is long, downstream converters are reporting resistance to high prices and have cut loads to avoid losses, and coastal MTO margins are deeply negative. With crude's next move hinging on whether Hormuz reopens or a deal is struck before the midterms, and with Chinese downstream demand showing "post-holiday restocking followed by price resistance", the balance of risk into the coming week is
high prices that hold only as long as the geopolitical premium does.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
October 9, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.



 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News

 4YRS

