Daily Chemical Market Price Overview — October 8, 2026
The first session after the National Day holiday delivered the broadest rally this series has recorded.
39 of 107 tracked products moved, 19 higher and 20 lower, and the gains were unusually large:
Sodium dodecyl sulfate jumped 45.59% to CNY 14,850/ton,
Copper sulfate rebounded 31.45% to CNY 25,633/ton,
Ammonium chloride rose 20.42% to CNY 867/ton and
Dichloromethane climbed 13.43% to CNY 2,568/ton. Two of those four are genuinely surprising and two are corrections, and each is examined in the cards below. The broad-based undertone was equally strong:
Methanol rose 5.34% to CNY 4,733/ton,
Propylene 2.78% to CNY 9,978/ton,
Benzene 2.63% to CNY 10,418/ton,
Lithium carbonate 2.50% to CNY 123,000/ton,
dimethyl carbonate 2.22% to CNY 6,167/ton,
PET 2.19% to CNY 8,942/ton and
ethyl acetate 2.13% to CNY 7,040/ton. Against that,
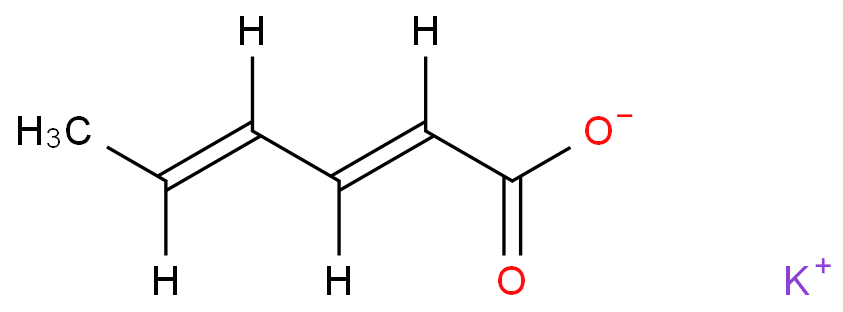
Potassium sorbate fell 24.50% to CNY 15,100/ton in a second consecutive reference reset, while
Dimethyl sulfoxide dropped 11.07% to CNY 10,850/ton and
Anthracite and
Cyanuric acid each lost 10.00%.
Three conditions shaped the session. First, the basket was refreshed over the holiday: 28 lines that appeared on September 29 have been retired and three new ones added, so week-on-week comparisons across that gap are not meaningful and this edition flags every level reset explicitly. Second, the energy complex was running hot into the holiday but cooled at the margin — November WTI settled at USD 88.28/barrel on October 7, down 1.30%, and December Brent at USD 100.20, down 0.38%, after reports that Saudi Arabia's East–West pipeline had restarted and that Washington and Tehran were edging toward talks, though Gulf shipping through Hormuz remains heavily restricted. Third, domestic signals were firmer than the macro backdrop: China's September manufacturing PMI returned above the 50 mark at 50.1%, Shanghai copper jumped 1.27%, and the September commodity price index reached a four-and-a-half-year high with the energy and chemical sub-indices up 14.8% and 13.7% respectively.

Top Price Movers
Sodium dodecyl sulfate, the anionic surfactant also known as SDS or K12, posted the largest single-day advance in the dataset, rising 45.59% to CNY 14,850/ton from CNY 10,200/ton. The move comes with an 11.65% weekly gain but a 5.62% monthly decline, which is the signature of a
reference reset rather than an organic rally: the product was carried at CNY 14,850/ton on September 29 and was then marked down to CNY 10,200/ton on October 7 before snapping back to its previous level today. Buyers should treat
CNY 14,850/ton as the operative reference and verify against supplier quotes. For context on where the true market sits, Chinese SDS is quoted in a wide band by grade — 93% content material around CNY 15,000/ton and food-grade around CNY 20,000/ton — so the tracked number is consistent with industrial grade. SDS demand is steady across detergents, toothpaste, textile dyeing, mineral flotation and building-materials foaming agents, and the lauric-alcohol feedstock chain has shown no disruption, so there is no fundamental basis for a move of this size.
Heads-up — the 45.59% print is a reference reset, not a market move: SDS was marked down to CNY 10,200/ton on October 7 and has simply returned to its long-standing CNY 14,850/ton level.
Copper sulfate rebounded 31.45% to CNY 25,633/ton, recovering almost exactly to the level it held on September 28 before it was marked down to CNY 23,650/ton on September 29. As with SDS, this is principally the
unwinding of an erroneous low reference — the weekly change is minus 2.45% and the monthly change is minus 17.39%, both inconsistent with a genuine one-day surge. Crucially, the move is
not confirmed by the underlying metal. Shanghai copper rose 1.27% on October 8 to close at CNY 110,260/ton, with spot 1# electrolytic copper at CNY 112,525–112,970/ton, up roughly CNY 580–1,690 depending on the assessment, while the futures price remains below where it sat before the holiday. Copper sulfate is consumed mainly in copper electrowinning, animal feed additives, fungicides for viticulture and water treatment, and none of those outlets has tightened. Copper concentrate treatment charges remain at historic lows and Chile's Centinela mine saw roughly 700 workers, 22% of the direct workforce, walk out on October 7, which supports metal prices at the margin, but the scale of today's sulfate print reflects accounting rather than those fundamentals.
Potassium sorbate fell 24.50% to CNY 15,100/ton from CNY 20,000/ton, the sharpest decline of the session. This is the
same CNY 15,100/ton level the product held on both September 28 and September 29 — the CNY 20,000/ton entry on October 7 was the anomaly, and today's move simply restores the established reference. The weekly change of plus 11.73% and the monthly change of plus 16.28% both point the same way, confirming that the underlying trend is not downward and that the decline is an artefact. The real market is well supplied: Chinese food-grade potassium sorbate is widely offered in the CNY 25–30 per kg range for drum quantities, down from over CNY 50 per kg earlier in the cycle, reflecting ample capacity in Shandong, Jiangsu and Hebei and only routine demand from preserved foods, beverages, sauces, cosmetics and feed. Buyers hunting for a genuine discount should expect little further downside from CNY 15,100/ton.
Price dropped 24.50% today — but this is a return to the CNY 15,100/ton level the product held through late September; the October 7 reading of CNY 20,000/ton was the outlier, and both the weekly and monthly trends remain positive.
Basic Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
4,860 |
0.21% |
0.64% |
17.66% |
| Acetic anhydride prices |
108-24-7 |
7,190 |
0.1% |
0.08% |
9.43% |
| Acetone prices |
67-64-1 |
8,369 |
-1.54% |
-1.31% |
-0.26% |
| Ammonium chloride prices |
12125-02-9 |
867 |
20.42% |
-0.25% |
-6.61% |
| Ammonium nitrate prices |
6484-52-2 |
4,150 |
0% |
0% |
0% |
| Ammonium sulfate prices |
7783-20-2 |
1,300 |
-0.99% |
-0.46% |
7.28% |
| Aniline prices |
62-53-3 |
14,900 |
0% |
0.58% |
7.76% |
| Benzene prices |
71-43-2 |
10,418 |
2.63% |
0.83% |
7.55% |
| Borax prices |
1303-96-4 |
6,520 |
0% |
0.09% |
3.26% |
| boric acid prices |
10043-35-3 |
11,600 |
0% |
0% |
0.47% |
| calcium carbide prices |
75-20-7 |
2,580 |
-6.18% |
-1.02% |
3.02% |
| Calcium chloride prices |
10043-52-4 |
1,413 |
0% |
0% |
5.21% |
| Caustic Soda prices |
68988-74-9 |
635 |
0% |
-0.16% |
-0.47% |
| Chloroform prices |
67-66-3 |
2,417 |
0% |
0% |
6.52% |
| Cobalt prices |
7440-48-4 |
262,900 |
-0.38% |
-0.09% |
-7.78% |
| Copper sulfate prices |
7758-98-7 |
25,633 |
31.45% |
-2.45% |
-17.39% |
| Dichloromethane prices |
75-09-2 |
2,568 |
13.43% |
-1.69% |
18.89% |
| Ethanol prices |
64-17-5 |
5,606 |
0% |
0.02% |
0.86% |
| ethyl acetate prices |
141-78-6 |
7,040 |
2.13% |
5.51% |
8.75% |
| Ethylene glycol prices |
107-21-1 |
6,425 |
0.39% |
-0.64% |
-1.72% |
| Ethylene Oxide prices |
75-21-8 |
9,700 |
0% |
0% |
7.93% |
| EVA prices |
- |
11,033 |
0% |
0% |
2.32% |
| Ferrous sulfate prices |
7720-78-7 |
500 |
0% |
0% |
0% |
| Formaldehyde prices |
50-00-0 |
1,813 |
1.97% |
0.79% |
6.01% |
| Formic acid prices |
64-18-6 |
2,000 |
0% |
-0.7% |
-11.58% |
| Heptane prices |
142-82-5 |
16,100 |
0% |
0% |
3.4% |
| Hexane prices |
110-54-3 |
10,325 |
0% |
0% |
5.43% |
| Hydrochloric acid prices |
7647-01-0 |
188 |
0% |
0.53% |
2.73% |
| Hydrogen peroxide prices |
7722-84-1 |
713 |
0% |
-0.14% |
3.18% |
| Iodine prices |
7553-56-2 |
640 |
0% |
0% |
0% |
| Kaolin prices |
1332-58-7 |
850 |
0% |
0% |
0% |
| Lithium carbonate prices |
554-13-2 |
123,000 |
2.5% |
0.03% |
-11.36% |
| Magnesium chloride prices |
7786-30-3 |
880 |
0% |
0% |
0% |
| Magnesium oxide prices |
1309-48-4 |
1,300 |
0% |
0% |
0% |
| Methanol prices |
67-56-1 |
4,733 |
5.34% |
0.8% |
16.57% |
| Nickel prices |
7440-02-0 |
122,233 |
-1.23% |
-0.67% |
-2.71% |
| Paraffin wax prices |
8002-74-2 |
9,800 |
0% |
0% |
0% |
| PET prices |
- |
8,942 |
2.19% |
0.63% |
2.55% |
| Phenol prices |
108-95-2 |
9,130 |
2.01% |
0.92% |
1.05% |
| Phosphoric Acid prices |
7664-38-2 |
8,375 |
0% |
0.05% |
-0.21% |
| Potassium carbonate prices |
584-08-7 |
7,450 |
0% |
-0.09% |
-0.63% |
| Potassium chloride prices |
7447-40-7 |
3,333 |
-0.51% |
-0.12% |
0.12% |
| Potassium nitrate prices |
7757-79-1 |
4,663 |
0% |
-0.04% |
-1.12% |
| Propylene prices |
115-07-1 |
9,978 |
2.78% |
0.72% |
1.46% |
| Propylene glycol prices |
57-55-6 |
9,117 |
-5.69% |
0.68% |
0.42% |
| PX prices |
- |
9,900 |
0% |
0.14% |
4.46% |
| Pyridine prices |
110-86-1 |
18,471 |
0% |
0% |
0.18% |
| Sodium bicarbonate prices |
144-55-8 |
1,200 |
0% |
0% |
-0.25% |
| Sodium carbonate prices |
497-19-8 |
1,260 |
0% |
0% |
0% |
| Sodium chloride prices |
7647-14-5 |
500 |
0% |
0% |
0% |
| Sodium hydroxide prices |
1310-73-2 |
2,567 |
0% |
0% |
1.1% |
| Sodium sulfate prices |
7757-82-6 |
560 |
0% |
0% |
0% |
| Sulfur prices |
7704-34-9 |
7,402 |
-3.9% |
-1.1% |
-4.46% |
| Sulfur hexafluoride prices |
2551-62-4 |
28,100 |
0% |
0% |
0% |
| sulfuric acid prices |
7664-93-9 |
1,710 |
0% |
-0.23% |
-4.47% |
| Titanium dioxide prices |
13463-67-7 |
14,220 |
0% |
0% |
0.44% |
| Toluene prices |
108-88-3 |
8,707 |
0% |
0.36% |
5.46% |
| Urea prices |
57-13-6 |
1,778 |
-0.11% |
-0.06% |
0.51% |
| White phosphorus prices |
12185-10-3 |
27,766 |
0% |
0% |
-0.25% |
| Xylene prices |
1330-20-7 |
8,520 |
0.2% |
0.11% |
0.91% |
| Zinc chloride prices |
7646-85-7 |
11,825 |
0% |
0% |
0% |
Basic chemicals saw
28 of 61 tracked products move, 15 higher and 13 lower, and the segment led the post-holiday advance. Setting aside the copper sulfate correction, the strongest gains were
Ammonium chloride up 20.42% to CNY 867/ton,
Dichloromethane up 13.43% to CNY 2,568/ton,
Methanol up 5.34% to CNY 4,733/ton,
Propylene up 2.78% to CNY 9,978/ton,
Benzene up 2.63% to CNY 10,418/ton,
Lithium carbonate up 2.50% to CNY 123,000/ton,
PET up 2.19% to CNY 8,942/ton,
ethyl acetate up 2.13% to CNY 7,040/ton and
Phenol up 2.01% to CNY 9,130/ton. Smaller advances came from
Acetic acid up 0.21% to CNY 4,860/ton and
HDPE up 0.12% to CNY 10,488/ton. Declines were led by
calcium carbide down 6.18% to CNY 2,580/ton,
Propylene glycol down 5.69% to CNY 9,117/ton,
Sulfur down 3.90% to CNY 7,402/ton,
Gasoline down 2.54% to CNY 10,020/ton,
Acetone down 1.54% to CNY 8,369/ton and
Nickel down 1.23% to CNY 122,233/ton.
Methanol was the defining story of the session. Spot rose 5.34% to CNY 4,733/ton, but the futures market went far further: the Zhengzhou MA2611 contract opened at CNY 3,450/ton, its low for the day, and locked limit-up at CNY 3,625/ton for a 9.02% gain, with turnover of 751,600 lots, open interest up 87,426 lots to 543,000 and a further 7% advance in the night session. The driver is physical, not speculative:
China's methanol port inventory fell 88,400 tonnes to 305,100 tonnes, the lowest on record and the tightest for this point of the year in five years, with East China down 79,900 tonnes and South China 8,500 tonnes. East China basis against the November contract reached CNY 975–1,051, in the 96th percentile historically. Imports are not filling the gap — August arrivals were 805,300 tonnes, down 188,300 tonnes month on month, Iranian loadings were only around 320,000 tonnes in August and Hormuz transits remain heavily restricted, so October imports are projected at just 430,000–450,000 tonnes. Inner Mongolia's Rongxin sold 3,000 tonnes at auction from a CNY 3,750/ton starting price up to CNY 4,000/ton, a CNY 250/ton premium, and Shanxi prompt prices reached CNY 4,014/ton against CNY 2,920–2,980/ton in early September. The monthly gain now stands at 16.57% and the annual comparison at 111.55%.
Ammonium chloride rose 20.42% to CNY 867/ton, another move that needs qualification. The product was tracked at CNY 845/ton on September 29 and CNY 810/ton on September 28, so the direction is genuine but the magnitude is partly a reference effect; the weekly change is minus 0.25% and the monthly change is minus 6.61%. The underlying market is nonetheless the tightest it has been in months. Urea prices have run to CNY 1,740–1,800/ton in parts of East China against CNY 500–570/ton for dry ammonium chloride, leaving an unusually wide spread that mechanically pulls ammonium chloride higher, and producers in Hebei, Shanxi and Shandong are running below saturation while pre-sold low-priced orders have left spot cargoes scarce, with some plants refusing new orders outright. Autumn demand is in its final phase and winter storage has not yet begun, so the near-term upside is capped, but the cost and availability picture remains supportive.
Dichloromethane added 13.43% to CNY 2,568/ton, the same pattern of a rebound off a low reading, with weekly and monthly changes of minus 1.69% and plus 18.89%; the genuine news is that major Shandong producers all raised ex-works offers on October 8, with Shandong Jinling up CNY 30/tonne, Dongyue up CNY 60/tonne to CNY 2,950/tonne, Dongying Huatai up CNY 40/tonne to CNY 2,930/tonne and Luxi Chemical at CNY 2,940/tonne. The product retains a 70.59% annual gain and sits in the top price band on 60-day, three-month and one-year measures, so traders expect a rebound-flavoured range rather than a fresh leg up.
Aromatics and the olefin chain moved as one, exactly as the crude-led cost story would predict.
Benzene gained 2.63% to CNY 10,418/ton after Dongying Fuhai Weilian lifted ex-works quotes by CNY 350/tonne to CNY 10,403/tonne, Wantong Petrochemical by CNY 390/tonne to CNY 10,407/tonne and Wudi Xinyue by CNY 350/tonne, pushing the annual gain to 78.12%.
Propylene rose 2.78% to CNY 9,978/ton with the annual comparison at 52.49%,
Phenol added 2.01% to CNY 9,130/ton and
Acetone slipped 1.54% to CNY 8,369/ton, the latter reflecting the normal post-holiday easing of co-product demand.
ethyl acetate advanced 2.13% to CNY 7,040/ton and now shows a 5.51% weekly and 8.75% monthly gain, and
Acetic acid edged 0.21% higher to CNY 4,860/ton with the annual comparison at 84.09%, its sharp rise over the past month driven by a heavy turnaround season that will keep supply short until November.
Lithium carbonate added 2.50% to CNY 123,000/ton as battery-grade material was assessed at CNY 123,750/ton, spodumene concentrate rose CNY 150/tonne to CNY 11,250/tonne on restocking by lithium salt plants and a large central-bank reverse repo improved liquidity conditions, and the 2701 futures contract touched CNY 125,900/ton intraday while battery-grade lithium hydroxide rose to CNY 116,000/ton.
The decline side of the segment was dominated by coal- and sulphur-linked chains, and by a genuine pullback in the diol.
calcium carbide fell 6.18% to CNY 2,580/ton, extending a weekly loss of 1.02%, as carbide furnaces that had been idled for maintenance in Shaanxi and Inner Mongolia progressively returned to service and post-holiday restocking demand faded; downstream PVC producers remain deeply loss-making and are buying only on a hand-to-mouth basis, with Wuha carbide quoted at CNY 2,425/ton and Inner Mongolia material around CNY 2,400/ton.
Sulfur dropped 3.90% to CNY 7,402/ton, taking the weekly loss to 1.10% and the monthly loss to 4.46%, as phosphate fertiliser producers cut consumption amid weak autumn demand — monoammonium phosphate fell 0.88% to CNY 3,743/tonne and ammonium sulfate 1.01% to CNY 1,300/tonne on the same day, and phosphate rock prices softened in response.
Propylene glycol eased 5.69% to CNY 9,117/ton, essentially a return to the CNY 9,100/ton level held on September 28, with the weekly and monthly changes of plus 0.68% and plus 0.42% confirming a flat underlying trend even as industry-wide propylene glycol quotes firmed 0.34% to CNY 9,700/ton.
Acetone slipped 1.54% to CNY 8,369/ton and
Nickel lost 1.23% to CNY 122,233/ton, the latter tracking a 1.84% fall in the Shanghai nickel contract as Indonesian supply continued to weigh on the stainless chain.
A large group of high-volume basics was unchanged, which is notable given how active the rest of the segment was.
Ethylene Oxide held at CNY 9,700/ton with a 53.97% annual gain,
Titanium dioxide at CNY 14,220/ton,
Epichlorohydrin at CNY 11,200/ton,
Aniline at CNY 14,900/ton with a 92.26% annual gain,
White phosphorus at CNY 27,766/ton,
EVA at CNY 11,033/ton,
Toluene at CNY 8,707/ton,
Xylene at CNY 8,520/ton,
Formic acid at CNY 2,000/ton,
Ethanol at CNY 5,606/ton,
sulfuric acid at CNY 1,710/ton,
soda ash at CNY 1,050/ton and
Caustic soda at CNY 635/ton. The most important of these is
WTI Crude Oil at USD 88/barrel, flat on the day but 2.20% lower on the week and 5.26% lower over the month, a reminder that the crude complex has been drifting down even as the chemical chains built on it rallied.
Phosphoric Acid at CNY 8,375/ton and
Ammonium sulfate at CNY 1,300/ton, down 3.35% from late September, round out a fertiliser picture that is weak at the phosphate end and tight at the nitrogen end. Overall, Basic Chemicals enters the fourth quarter carrying a
strong cost-push impulse from methanol and aromatics, a genuine supply squeeze in the methanol and ammonium chloride chains, and clear softness in sulphur, carbide and nickel.
Fine Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Activated carbon prices |
64365-11-3 |
4,200 |
0% |
0% |
0% |
| antifreeze prices |
- |
800 |
0% |
0% |
0% |
| Castor oil prices |
8001-79-4 |
14,500 |
0% |
0% |
1.3% |
| Citric acid prices |
77-92-9 |
6,200 |
0% |
0% |
0% |
| Cocamidopropyl betaine prices |
61789-40-0 |
6,000 |
0% |
0% |
0% |
| Creatine monohydrate prices |
6020-87-7 |
20,980 |
-0.1% |
-0.25% |
-0.2% |
| Cyanuric acid prices |
108-80-5 |
7,650 |
-10% |
-2.71% |
2.89% |
| dimethyl carbonate prices |
616-38-6 |
6,167 |
2.22% |
-0.38% |
-4.23% |
| Dimethyl sulfoxide prices |
67-68-5 |
10,850 |
-11.07% |
2.08% |
5.18% |
| Ferric chloride prices |
7705-08-0 |
2,808 |
0% |
0% |
0.07% |
| glycolic acid prices |
79-14-1 |
13,000 |
0% |
0% |
0% |
| Guar gum prices |
9000-30-0 |
15,500 |
0% |
0% |
0% |
| Hydroquinone prices |
123-31-9 |
30,500 |
0% |
0% |
0% |
| Imidazole prices |
288-32-4 |
21,750 |
-1.14% |
-0.28% |
0.5% |
| Lactic acid prices |
50-21-5 |
8,163 |
0% |
0% |
0.55% |
| Magnesium glycinate prices |
14783-68-7 |
29,000 |
0% |
0% |
0% |
| Mannitol prices |
87-78-5 |
18,000 |
0% |
0% |
0% |
| Melamine prices |
108-78-1 |
6,325 |
0% |
0.06% |
1.1% |
| Melatonin prices |
73-31-4 |
850 |
0% |
0% |
0% |
| Oleic acid prices |
112-80-1 |
10,000 |
0% |
0% |
0% |
| Petroleum prices |
8009-03-8 |
9,300 |
0% |
0% |
0% |
| Potassium Citrate prices |
866-84-2 |
8,600 |
-4.97% |
0.36% |
-1.3% |
| Potassium iodide prices |
7681-11-0 |
45,000 |
0% |
0% |
0% |
| Potassium sorbate prices |
24634-61-5 |
15,100 |
-24.5% |
11.73% |
16.28% |
| Quartz prices |
14808-60-7 |
6,800 |
0% |
0% |
0% |
| Retinol prices |
68-26-8 |
55 |
0% |
0% |
0% |
| sodium acetate prices |
127-09-3 |
5,500 |
0% |
0.09% |
0.44% |
| Sodium benzoate prices |
532-32-1 |
850 |
0% |
0% |
0% |
| Sodium dodecyl sulfate prices |
151-21-3 |
14,850 |
45.59% |
11.65% |
-5.62% |
| Sodium hypochlorite prices |
7681-52-9 |
553 |
0% |
0% |
0% |
| Sodium metabisulfite prices |
7681-57-4 |
3,903 |
-0.18% |
-0.08% |
-0.99% |
| Sodium polyacrylate prices |
9003-04-7 |
18,000 |
0% |
0% |
0% |
| Stearic acid prices |
57-11-4 |
28,000 |
0% |
0% |
0% |
| Trichloroethylene prices |
79-01-6 |
4,375 |
-8.85% |
-1.49% |
9.02% |
| Water softener salt prices |
- |
967 |
0% |
0% |
0% |
| Xanthan gum prices |
11138-66-2 |
21,000 |
0% |
0% |
0% |
Fine Chemicals saw
10 of 36 products move, 4 higher and 6 lower, and every one of the four largest moves was a reference event rather than a market event.
Sodium dodecyl sulfate jumped 45.59% to CNY 14,850/ton and
Potassium sorbate plunged 24.50% to CNY 15,100/ton, both discussed above. Beneath them,
Dimethyl sulfoxide fell 11.07% to CNY 10,850/ton, a third consecutive flat reading at that level that follows the same CNY 10,850/ton print on October 7, with the weekly and monthly changes of plus 2.08% and plus 5.18% confirming a firm underlying trend; market quotes for 99.9% material range from CNY 9,500 to CNY 10,700/ton and the standard benchmark sat unchanged at CNY 12,200/tonne on October 7, so the tracked figure sits at the low end of the real range.
Cyanuric acid fell 10.00% to CNY 7,650/ton, retracing the full extent of its 11.11% jump on September 29 — a textbook reference reset, with weekly and monthly changes of minus 2.71% and plus 2.89%. Actual Chinese offers for 98.5% cyanuric acid cluster between CNY 5,100 and CNY 8,500/ton depending on producer, so the tracked level is at the top of the range.
Trichloroethylene eased 8.85% to CNY 4,375/ton, recovering part of the ground lost on September 29 when it fell to CNY 4,314/ton, but the move is a rebound rather than a decline in trend terms and the product still carries a 9.02% monthly gain against a 1.49% weekly loss. Metal degreasing and vapour cleaning demand is steady rather than expanding and the hydrofluorocarbon feedstock outlet remains soft, so the level looks sustainable.
Potassium Citrate slipped 4.97% to CNY 8,600/ton from CNY 9,050/ton, with a 0.36% weekly gain and a 1.30% monthly loss.
dimethyl carbonate added 2.22% to CNY 6,167/ton, though the weekly change of minus 0.38% and the monthly change of minus 4.23% show the product has cooled considerably from the exceptional run it enjoyed in September, when it was the largest monthly gainer in the basket.
Imidazole eased 1.14% to CNY 21,750/ton and
Sodium benzoate and
Creatine monohydrate moved fractionally lower.
The overwhelming majority of the speciality and ingredient lines were completely unchanged, which is characteristic of contract-priced product.
Citric acid held at CNY 6,200/ton,
Lactic acid at CNY 8,163/ton,
Hydroquinone at CNY 30,500/ton,
Oleic acid at CNY 10,000/ton,
glycolic acid at CNY 13,000/ton,
Melamine at CNY 6,325/ton,
Ferric chloride at CNY 2,808/ton,
Sodium hypochlorite at CNY 553/ton,
Water softener salt at CNY 967/ton,
Mannitol at CNY 18,000/ton,
Stearic acid at CNY 28,000/ton,
Sodium polyacrylate at CNY 18,000/ton,
Xanthan gum at CNY 21,000/ton,
Guar gum at CNY 15,500/ton,
Castor oil at CNY 14,500/ton,
Quartz at CNY 6,800/ton,
Cocamidopropyl betaine at CNY 6,000/ton,
Activated carbon at CNY 4,200/ton,
sodium acetate at CNY 5,450/ton,
Sodium metabisulfite at CNY 3,910/ton and
Melatonin at CNY 850/kg. Three lines entered the basket this edition —
Potassium iodide,
Potassium nitrate and
Retinol — and all three opened flat, so their first readings should be treated as indicative only.
Magnesium glycinate at CNY 29,000/ton and
antifreeze round out a segment whose pricing is essentially unchanged entering the fourth quarter.
The practical takeaway for buyers of fine chemicals is that
none of today's large numbers are tradeable signals. Sodium dodecyl sulfate, potassium sorbate, cyanuric acid and dimethyl sulfoxide all moved because their references were being re-established after the holiday break, not because supply or demand shifted. The genuine and modest signals in the segment point in opposite directions — dimethyl carbonate and potassium citrate softer on the month, dimethyl sulfoxide and trichloroethylene firmer on the month. With Chinese speciality producers typically issuing fresh price lists in the second week of October, the coming week's readings will be considerably more informative than today's.
Energy, Rubber, Plastic and other chemicals Prices
Energy, Rubber, Plastic and other chemicals saw
4 of 10 products move, 1 higher and 3 lower.
Anthracite fell 10.00% to CNY 1,575/ton,
Gasoline lost 2.54% to CNY 10,020/ton and
Asphalt eased 0.63% to CNY 6,310/ton, while
ABS was the lone gainer, up 1.77% to CNY 11,517/ton.
WTI Crude Oil at USD 88/barrel,
Carbon Black at CNY 11,693/ton,
Silica at CNY 6,400/ton,
HDPE at CNY 10,488/ton,
Carbon at CNY 12,467/ton and
anaerobic bacteria at CNY 50/kg were all unchanged. The segment is now the clearest illustration of how differently the energy-linked and coal-linked chains have behaved since the holiday.
Anthracite showed the largest decline, dropping 10.00% to CNY 1,575/ton, precisely retracing the level it held on September 23. The weekly change of minus 1.10% and the monthly change of plus 1.19% show that nothing fundamental has changed: the coal complex is fully supplied, pithead prices across Shanxi, Shaanxi and Inner Mongolia have been broadly stable through the holiday, and the seasonal winter-stocking bid has so far been concentrated in high-quality anthracite lump for household heating rather than in the tracked grades. Thermal coal for power generation was quoted flat at CNY 994.50/tonne on October 8 while coking coal eased 2.64% to CNY 2,273.75/tonne, and the market is watching coal prices as the next input that could either relieve or deepen steel and carbide margins.
Gasoline fell 2.54% to CNY 10,020/ton, tracking the 2.61% drop in 92-octane wholesale assessments to CNY 10,019.57/tonne and the 2.27% fall in 0-octane diesel to CNY 9,404.86/tonne as holiday travel demand faded, though refinery runs remain low and product inventories tight, which should limit the pullback. Fuel oil assessments in Shanghai and Qingdao were also cut, and 180CST fell 0.99% to CNY 7,562.50/tonne.
The polymer and rubber chains diverged sharply.
ABS rose 1.77% to CNY 11,517/ton with a 0.72% weekly and 0.87% monthly gain, corroborated by a 2.65% rise in Yuyao ABS 0215A to CNY 11,600/tonne and by styrene jumping 8.58% to CNY 11,520/tonne, which restores a meaningful cost push into the acrylonitrile-butadiene-styrene chain.
HDPE was flat at CNY 10,488/ton even as the broader polyolefin complex rallied hard, with LLDPE up 2.37% to CNY 9,500/tonne in North China, polypropylene raffia up 2.58% to CNY 10,190/tonne, PET up 2.20% to CNY 8,942.08/tonne and polystyrene up 1.50% to CNY 11,300/tonne.
Carbon Black was unchanged at CNY 11,693/ton with a 3.18% monthly gain, still caught between high-temperature coal tar at roughly 65%–80% of production cost and weak tyre demand, though the industry's fourth round of price increases this year is now being implemented.
Silica held at CNY 6,400/ton with a 2.88% monthly gain and
Carbon at CNY 12,467/ton. Notably, Chinese semi-steel tyre sample capacity utilisation stood at 65.17% at the end of September and all-steel at 61.52%, both well below year-earlier levels, so the pass-through of higher feedstock costs remains the dominant theme rather than volume growth.
Overall, the Energy, Rubber, Plastic and other chemicals segment is defined by
crude-linked chains riding a geopolitical premium while coal-linked chains deflate on ample supply. Crude itself is the clearest illustration of the tension: WTI closed October 7 at USD 88.28/barrel, down 1.30%, and Brent December at USD 100.20, down 0.38%, after Saudi Arabia's East–West pipeline restarted and Washington and Tehran signalled a willingness to talk, yet Gulf shipping through Hormuz remains a fraction of pre-conflict volumes and the market is reported to be pricing a Brent target of USD 80–85/barrel only if a substantive agreement emerges. Against that, domestic coal, carbide, coke and anthracite all point lower as maintenance-restricted capacity returns. The implication for the fourth quarter is that
oil-derived cost push is real but fragile, and coal-derived cost support is fading, which leaves polymers and rubber chemicals exposed if crude gives back its risk premium before demand recovers.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
October 8, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News

 13YRS

