Daily Chemical Market Price Overview — June 29, 2026
The latest daily chemical price update highlights key movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy, and
Plastics. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better monitor short-term market volatility and broader pricing trends throughout the chemical supply chain.
Market attention today focused on the sharp rebound in
Tetrahydrofuran (THF) and
Propylene, supported by supply tightening and downstream replenishment demand, while
PX,
ABS, and several bulk solvents remained under pressure amid weak polyester consumption, cautious purchasing activity, and softer energy markets. Meanwhile, declining crude oil prices continued to influence sentiment across both energy and petrochemical sectors.
Top Price Movers
Tetrahydrofuran recorded the strongest daily gain across today's chemical market. Prices surged as spot availability tightened and downstream demand from PTMEG, spandex, and lithium battery material sectors remained active. Rising upstream BDO costs and cautious producer sales strategies further supported the rally. Although monthly gains remain modest at 2.17%, the sharp daily increase indicates a significant recovery in market sentiment.
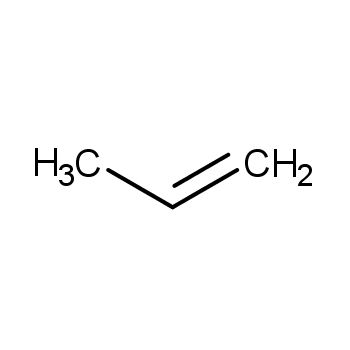
Propylene posted the second-largest daily increase, rising more than 5% as downstream polypropylene and propylene oxide producers increased replenishment purchases. Short-term supply tightening and improved trading activity also contributed to the rebound. Despite the strong daily gain, monthly prices remain down 11.69%, suggesting that the market is recovering from previous oversupply pressure.
PX experienced the largest daily decline among all monitored products. Weak polyester and PTA demand continued to weigh on the market, while ample inventories and cautious downstream purchasing further pressured prices. Monthly prices remain down 9.16%, reflecting persistent oversupply and soft end-use demand across the polyester value chain.
Price dropped 10.23% today — Attractive sourcing window for polyester and PTA buyers.
Basic Chemicals Prices
| Product |
CAS |
Price (CNY/TON) |
Daily |
Weekly |
Monthly |
| Acetone prices |
67-64-1 |
5,013 |
-0.73% |
0% |
-17.22% |
| Ammonium sulfate prices |
7783-20-2 |
1,257 |
-3.53% |
0% |
0% |
| Benzene prices |
71-43-2 |
6,737 |
0.51% |
0% |
-12.18% |
| Boric acid prices |
10043-35-3 |
11,017 |
-0.15% |
0% |
1.7% |
| Caustic Soda prices |
68988-74-9 |
669 |
-0.15% |
0% |
3.53% |
| Cobalt prices |
7440-48-4 |
380,000 |
0.11% |
0% |
-6.42% |
| Dichloromethane prices |
75-09-2 |
1,960 |
-1.41% |
0% |
-7.09% |
| Ethylene glycol prices |
107-21-1 |
4,443 |
0.11% |
0% |
-7.85% |
| Hexane prices |
110-54-3 |
7,675 |
-0.97% |
0% |
1.1% |
| Hydrochloric acid prices |
7647-01-0 |
182 |
-3.19% |
0% |
33.12% |
| Hydrogen peroxide prices |
7722-84-1 |
640 |
1.11% |
0% |
-30.24% |
| Isopropyl alcohol prices |
67-63-0 |
6,208 |
-3% |
0% |
-14.57% |
| Lithium carbonate prices |
554-13-2 |
149,000 |
-0.67% |
0% |
-10.93% |
| Methanol prices |
67-56-1 |
2,813 |
1.48% |
0% |
-2.8% |
| Nickel prices |
7440-02-0 |
129,317 |
1.19% |
0% |
-6.74% |
| PET prices |
- |
7,150 |
-0.35% |
0% |
-11.78% |
| Phenol prices |
108-95-2 |
7,450 |
-0.67% |
0% |
-1.47% |
| Phosphoric Acid prices |
7664-38-2 |
10,438 |
-2.22% |
0% |
17.64% |
| Propylene prices |
115-07-1 |
7,211 |
5.25% |
0% |
-11.69% |
| PX prices |
- |
7,900 |
-10.23% |
0% |
-9.16% |
| Sodium bicarbonate prices |
144-55-8 |
1,218 |
-0.16% |
0% |
-0.97% |
| Sodium hydroxide prices |
1310-73-2 |
2,667 |
-1.22% |
0% |
-6.41% |
| Sulfur prices |
7704-34-9 |
8,736 |
0.39% |
0% |
24.41% |
| Toluene prices |
108-88-3 |
5,728 |
-0.97% |
0% |
-6.35% |
| Urea prices |
57-13-6 |
1,811 |
-0.28% |
0% |
-0.6% |
| White phosphorus prices |
12185-10-3 |
31,129 |
-3.61% |
0% |
7.89% |
| Xylene prices |
1330-20-7 |
5,811 |
-0.68% |
0% |
-4.7% |
Basic chemicals showed a mixed performance on June 29, with upstream aromatics and solvents remaining under pressure while selected energy and olefin products rebounded.
PX, Isopropyl alcohol, Ammonium sulfate, Hydrochloric acid, and White phosphorus recorded notable declines as downstream procurement remained cautious and inventories stayed relatively sufficient. Meanwhile,
Propylene, Methanol, Nickel, Hydrogen peroxide, and Sulfur posted gains, supported by short-term restocking activity and stronger raw material sentiment. Although
Propylene surged more than 5% day on day, its monthly decline remained above 11%, indicating that the market is still recovering from previous oversupply pressure. In contrast,
PX dropped more than 10% in a single day amid weak polyester demand, while
Phosphoric Acid continued to maintain strong monthly gains despite the latest correction.
Recent market sentiment across the Asian chemical chain remains heavily influenced by weak downstream consumption and volatile energy markets. The aromatics sector continues to face pressure as polyester and PTA demand remains below expectations, weighing on
PX, PET, Toluene, and Xylene prices. At the same time, several market reports indicate that China's coal-to-chemical sector is expanding, supporting products such as
Methanol and other coal-based intermediates. Geopolitical disruptions affecting Middle East energy supply and logistics earlier this year have also increased market volatility, although recent easing in shipping conditions has reduced some cost pressures. Meanwhile, industrial restocking and improved procurement activity have provided support for products including
Sulfur, Phosphoric Acid, and selected metals such as Nickel and Cobalt.
Fine Chemicals Prices
Fine chemicals recorded a strong upward movement on June 29, led by
Tetrahydrofuran (THF), which surged 11.76% day on day to CNY 19,000/ton. The sharp increase reflects tightening spot availability and active replenishment demand from downstream spandex, PTMEG, lithium battery materials, and specialty solvent sectors. Although the monthly increase remained relatively moderate at 2.17%, the latest rally suggests that market sentiment has improved significantly after a prolonged period of weak pricing. Rising feedstock costs and cautious producer sales strategies also contributed to the upward momentum, resulting in a rapid recovery of spot quotations.
Industry News Background: The recent increase in
Tetrahydrofuran (THF) prices is closely associated with developments in the upstream
1,4-Butanediol (BDO) market. The European Union recently imposed anti-dumping duties on BDO imports from China, Saudi Arabia, and the United States, potentially reshaping global supply flows and increasing market attention toward BDO-related products. At the same time, downstream demand from PTMEG, spandex, and specialty polymer applications continues to provide structural support for THF consumption. Global market forecasts also indicate stable long-term growth in THF demand driven by engineering plastics, battery materials, and high-performance solvent applications, supporting positive sentiment across the fine chemicals sector.
Energy and Plastic Chemicals Prices
Energy and plastic chemicals displayed a mixed trend on June 29, with weakness in crude oil and engineering plastics partially offset by firmer asphalt and polyethylene markets.
WTI Crude Oil fell 4.17% day on day to USD 69/bbl, extending its monthly decline to more than 15% as geopolitical risk premiums eased and concerns over oversupply resurfaced. In the plastics segment,
ABS continued to weaken, declining 1.88% on the day and more than 14% on a monthly basis amid sluggish demand from the home appliance and consumer electronics sectors. Meanwhile,
HDPE posted a modest gain of 0.51%, supported by short-term restocking activity and relatively stable packaging demand. In the energy complex,
Asphalt prices increased 1.05%, benefiting from seasonal infrastructure demand and firmer construction activity despite lower crude prices.
Industry News Background: Global oil markets recently came under pressure as concerns over supply disruptions in the Middle East eased and investors refocused on increasing production from major producers and slowing global fuel demand growth. The decline in crude prices has weakened cost support for downstream petrochemicals, contributing to softer pricing in products such as
ABS. However, China's infrastructure spending and seasonal road construction activities continue to support
Asphalt consumption. In the plastics market, demand remains differentiated, with packaging applications providing resilience for
HDPE, while engineering plastics and durable consumer goods continue to face weak end-market conditions. Market participants are also closely monitoring potential stimulus measures in China and the pace of manufacturing recovery, which could influence demand for both energy and plastic chemicals in the coming months.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
June 29, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News



