Daily Chemical Market Price Overview — August 10, 2026
The latest daily chemical price update highlights key movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy,
Plastics, and
Rubber. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better track short-term market volatility and broader pricing trends across the chemical supply chain.
Market focus today centered on sharp gains in
Iron Powder,
Trichloroacetic Acid,
PTMEG, and
Dimethyl Sulfoxide (DMSO), driven by supply tightness and active replenishment demand in selected specialty chemical segments. Meanwhile,
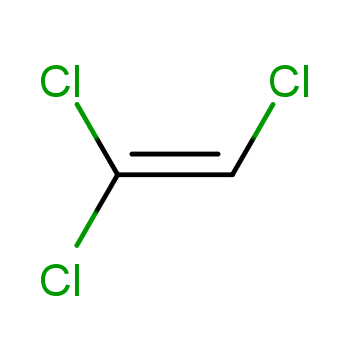
Trichloroethylene,
Hydrochloric Acid, and
Dichloromethane experienced notable declines amid oversupply concerns and cautious downstream purchasing. Across the broader market, firm crude oil prices continued to support energy-related products, while plastics and rubber markets maintained a modest upward trend backed by stable feedstock costs.

Top Price Movers
Iron Powder recorded the strongest daily increase across all monitored commodities, surging nearly 49% day-on-day. The sharp jump likely reflects tight spot supply, low inventory availability, or isolated high-priced transactions rather than a broad-based recovery in industrial demand. Despite the strong daily rebound, monthly prices remain down 13.35%, indicating that the market is still recovering from previous weakness.
Trichloroacetic Acid posted the second-largest gain of the day as supply availability tightened and procurement activity from pharmaceutical and specialty chemical sectors improved. The market remains relatively balanced on a monthly basis, suggesting the latest increase was primarily driven by short-term supply constraints and replenishment demand rather than a structural shift in consumption.
Trichloroethylene registered the largest decline in today's market, falling more than 24% as downstream demand from metal cleaning and industrial solvent applications remained weak. Increased market availability and cautious purchasing sentiment further pressured prices. Monthly prices are also down 3.84%, indicating that the market continues to face oversupply challenges.
Price dropped 24.47% today — Attractive sourcing window for chlorinated solvent buyers.
Basic Chemicals Prices
| Product |
CAS |
Price (CNY/TON) |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
3,070 |
-1.29% |
-2.07% |
-1.07% |
| Acetone prices |
67-64-1 |
6,300 |
1.4% |
-1.22% |
10.9% |
| Benzene prices |
71-43-2 |
7,434 |
0.45% |
-0.23% |
-1.14% |
| Caustic Soda prices |
68988-74-9 |
639 |
-0.31% |
0% |
-0.77% |
| Cobalt prices |
7440-48-4 |
330,700 |
-0.57% |
0% |
-7.66% |
| Dichloromethane prices |
75-09-2 |
2,025 |
-2.32% |
0% |
1.57% |
| Ethylene glycol prices |
107-21-1 |
5,067 |
0.4% |
0% |
10.3% |
| EVA prices |
- |
10,333 |
-0.48% |
0% |
4.66% |
| Ferrous sulfate prices |
7720-78-7 |
280 |
14.29% |
-19.54% |
8.02% |
| Formaldehyde prices |
50-00-0 |
1,229 |
-0.49% |
-0.72% |
-1.81% |
| Heptane prices |
142-82-5 |
15,800 |
-1.25% |
0% |
10% |
| Hydrochloric acid prices |
7647-01-0 |
168 |
-10.64% |
0% |
2.7% |
| Hydrogen peroxide prices |
7722-84-1 |
610 |
2.18% |
0% |
-9.25% |
| Iron prices |
7439-89-6 |
6,100 |
48.78% |
0% |
-13.35% |
| Isopropyl alcohol prices |
67-63-0 |
6,950 |
0.48% |
0.6% |
3.77% |
| Lithium carbonate prices |
554-13-2 |
143,000 |
1.42% |
0.61% |
-7.67% |
| Methanol prices |
67-56-1 |
2,580 |
0.78% |
-0.51% |
-2.16% |
| Nickel prices |
7440-02-0 |
130,717 |
0.5% |
0% |
1.15% |
| Phenol prices |
108-95-2 |
8,410 |
-0.18% |
-2.01% |
6.26% |
| Propylene prices |
115-07-1 |
8,161 |
0.33% |
0% |
-1.59% |
| Propylene glycol prices |
57-55-6 |
9,333 |
1.81% |
0% |
4.47% |
| Sodium carbonate prices |
497-19-8 |
1,300 |
8.33% |
22.65% |
5.75% |
| Sulfur prices |
7704-34-9 |
9,436 |
-1.05% |
0.68% |
2.1% |
| Toluene prices |
108-88-3 |
6,633 |
2.84% |
0.19% |
2.82% |
| Urea prices |
57-13-6 |
1,735 |
-0.91% |
0.11% |
-1.74% |
| White phosphorus prices |
12185-10-3 |
27,896 |
1.21% |
0% |
2.17% |
| Xylene prices |
1330-20-7 |
6,660 |
1.42% |
2.01% |
5.91% |
China's
Basic Chemicals market showed a mixed performance on August 10. Among bulk petrochemical products,
Acetone,
Toluene,
Xylene, and
Ethylene Glycol posted moderate gains, supported by firmer feedstock costs and improved replenishment demand from downstream industries. Aromatics sentiment remained relatively stable despite ongoing concerns over regional oversupply and fluctuating crude oil trends, helping Benzene edge slightly higher. Meanwhile,
Acetic Acid,
Dichloromethane, and
Hydrochloric Acid weakened as downstream procurement remained cautious and spot inventories increased. The sharpest decline was observed in Hydrochloric Acid, which fell more than 10% day-on-day amid oversupply pressure. On the metals side,
Lithium Carbonate advanced 1.42%, reflecting continued support from the battery and energy storage sectors despite remaining below year-ago levels.
Soda Ash surged 8.33% daily and more than 22% weekly, indicating active restocking and tightening spot availability after an extended period of weak market conditions. Notably,
Iron Powder jumped nearly 49% day-on-day, suggesting supply-side disruptions or isolated market transactions rather than a broad-based demand recovery. Overall, the market remained characterized by selective buying activity, with feedstock-sensitive chemicals outperforming while demand-driven products continued to face pressure.
Recent industry developments continue to influence pricing trends across chemical and battery material markets. Asian aromatics markets, including
Benzene,
Toluene, and
Xylene, have been affected by shifting crude oil expectations and concerns over regional petrochemical oversupply, although downstream replenishment has provided short-term support. Meanwhile, the
Lithium Carbonate market remains sensitive to supply-side disruptions and battery-sector demand, with global lithium prices recovering from previous lows due to tighter raw material availability and continued growth in energy storage applications. These factors have helped support near-term sentiment for battery materials despite ongoing concerns regarding future supply expansion. Market participants are expected to closely monitor feedstock costs, inventory levels, and downstream operating rates in the coming weeks.
Fine Chemicals Prices
China's
Fine Chemicals market recorded significant volatility on August 10, driven by a combination of supply-side adjustments and selective downstream replenishment. The strongest gains were observed in
Trichloroacetic Acid, which surged 33.33% day-on-day, and
PTMEG (Polytetrahydrofuran Ether Glycol), which climbed 11.76%, supported by tightening spot availability and improving demand from the spandex and specialty materials sectors.
Dimethyl Sulfoxide (DMSO) also rose 11.63%, reflecting active procurement from pharmaceutical, electronics, and battery-related applications following previous market weakness. In the oleochemical segment,
Lauric Acid increased 7.14%, benefiting from firmer feedstock fatty acid costs and restocking activity. In contrast,
Trichloroethylene dropped sharply by 24.47%, suggesting oversupply pressure and sluggish downstream consumption from metal cleaning and industrial solvent markets.
Oleic Acid declined 2.56% on the day, although monthly gains remained close to 15%, indicating that the broader oleochemical market continues to trade above earlier summer levels. Overall, the Fine Chemicals sector showed stronger momentum than bulk chemicals, with specialty products linked to pharmaceuticals, advanced materials, and high-value industrial applications outperforming traditional solvent markets.
Recent developments across specialty chemical value chains continue to provide support for selected Fine Chemicals. The global
DMSO market is benefiting from growing demand in pharmaceutical formulations, semiconductor processing, and lithium battery manufacturing, with electronic-grade demand emerging as one of the fastest-growing application segments. Meanwhile,
PTMEG market sentiment has improved alongside recovering operating rates in the spandex industry, helping support demand for polyurethane and elastic fiber intermediates. In the oleochemical sector,
Lauric Acid and
Oleic Acid remain closely linked to Southeast Asian palm oil feedstock trends, with fluctuations in palm oil prices continuing to influence fatty acid costs and procurement strategies. Market participants are also monitoring supply chain developments in specialty chlorinated chemicals, where production adjustments and environmental compliance requirements have contributed to tighter availability for products such as
Trichloroacetic Acid. Looking ahead, downstream operating rates, feedstock cost movements, and inventory replenishment cycles are expected to remain the primary drivers of Fine Chemicals pricing.
Energy, Rubber and Plastics chemicals Prices
China's
Fine Chemicals market recorded significant volatility on August 10, driven by a combination of supply-side adjustments and selective downstream replenishment. The strongest gains were observed in
Trichloroacetic Acid, which surged 33.33% day-on-day, and
PTMEG (Polytetrahydrofuran Ether Glycol), which climbed 11.76%, supported by tightening spot availability and improving demand from the spandex and specialty materials sectors.
Dimethyl Sulfoxide (DMSO) also rose 11.63%, reflecting active procurement from pharmaceutical, electronics, and battery-related applications following previous market weakness. In the oleochemical segment,
Lauric Acid increased 7.14%, benefiting from firmer feedstock fatty acid costs and restocking activity. In contrast,
Trichloroethylene dropped sharply by 24.47%, suggesting oversupply pressure and sluggish downstream consumption from metal cleaning and industrial solvent markets.
Oleic Acid declined 2.56% on the day, although monthly gains remained close to 15%, indicating that the broader oleochemical market continues to trade above earlier summer levels. Overall, the Fine Chemicals sector showed stronger momentum than bulk chemicals, with specialty products linked to pharmaceuticals, advanced materials, and high-value industrial applications outperforming traditional solvent markets. Recent developments across specialty chemical value chains continue to provide support for selected Fine Chemicals. The global
DMSO market is benefiting from growing demand in pharmaceutical formulations, semiconductor processing, and lithium battery manufacturing, with electronic-grade demand emerging as one of the fastest-growing application segments. Meanwhile,
PTMEG market sentiment has improved alongside recovering operating rates in the spandex industry, helping support demand for polyurethane and elastic fiber intermediates. In the oleochemical sector,
Lauric Acid and
Oleic Acid remain closely linked to Southeast Asian palm oil feedstock trends, with fluctuations in palm oil prices continuing to influence fatty acid costs and procurement strategies. Market participants are also monitoring supply chain developments in specialty chlorinated chemicals, where production adjustments and environmental compliance requirements have contributed to tighter availability for products such as
Trichloroacetic Acid. Looking ahead, downstream operating rates, feedstock cost movements, and inventory replenishment cycles are expected to remain the primary drivers of Fine Chemicals pricing.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
August 10, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 3YRS

