Daily Chemical Market Price Overview — August 12, 2026
The latest daily chemical price update highlights key movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy, and
Plastics. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better monitor short-term market volatility, identify emerging procurement opportunities, and track broader pricing trends across the chemical supply chain.
Market focus today centered on the sharp surge in
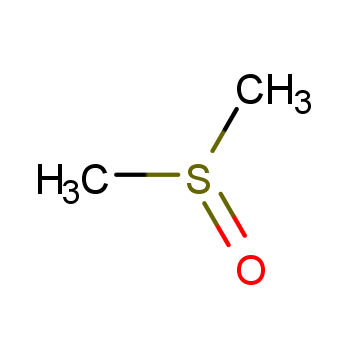
Dimethyl Sulfoxide (DMSO), continued strength in
Lithium Carbonate and
PTMEG, and firmer sentiment across energy markets as
WTI crude oil extended its gains. Meanwhile,
Calcium Carbonate,
Isopropyl Alcohol, and several commodity chemicals remained under pressure due to cautious downstream purchasing and ample market supply, highlighting increasingly divergent conditions between specialty chemicals and traditional industrial materials.
Top Price Movers
Dimethyl sulfoxide (DMSO) recorded the strongest daily increase across all monitored products. The sharp rise was driven by tight spot supply, producer maintenance activities, and improved procurement from pharmaceutical and electronics-related downstream sectors. Weekly gains also reached 11.63%, indicating that short-term market availability remains constrained despite monthly prices still being slightly below previous levels.
Lithium carbonate posted the second-largest gain of the day, supported by tighter supply expectations, inventory normalization, and continued demand from the electric vehicle and energy storage sectors. The product has now advanced 2.40% on a weekly basis, suggesting that battery-material sentiment has improved following a prolonged period of market weakness.
PTMEG prices strengthened significantly as stable spandex demand and expectations of tighter feedstock supply improved market confidence. Although weekly prices remain slightly lower, the strong daily rebound highlights continued volatility in the polyester and elastane value chain, where operating-rate adjustments can quickly affect market balances.
Calcium carbonate registered the largest decline among all tracked products. The drop reflects persistent oversupply, weak construction-material demand, and intense competition among domestic producers. Monthly prices remain down more than 50%, highlighting the severity of the downturn across building-material and industrial filler markets.
Price dropped 4.00% today — Attractive sourcing window for construction and industrial mineral buyers.
Basic Chemicals Prices
| Product |
CAS |
Price (CNY/TON) |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
3,047 |
-0.2% |
-2.07% |
-1.6% |
| Acetone prices |
67-64-1 |
6,400 |
-0.59% |
1.62% |
11.63% |
| Ammonium sulfate prices |
7783-20-2 |
1,143 |
-0.61% |
0.93% |
0.09% |
| Aniline prices |
62-53-3 |
11,825 |
1.72% |
0.37% |
7.58% |
| Borax prices |
1303-96-4 |
5,710 |
0.88% |
0.12% |
6.2% |
| Cobalt prices |
7440-48-4 |
327,700 |
-0.3% |
-2.73% |
-8.21% |
| Dichloromethane prices |
75-09-2 |
1,975 |
-1.45% |
-3.88% |
0.66% |
| Ethanol prices |
64-17-5 |
5,531 |
-0.81% |
-0.04% |
-0.45% |
| Ethyl acetate prices |
141-78-6 |
5,843 |
2.35% |
1.39% |
0.8% |
| Ethylene glycol prices |
107-21-1 |
5,120 |
1.65% |
-1.06% |
10.17% |
| Formaldehyde prices |
50-00-0 |
1,230 |
0.08% |
-1.21% |
-2.2% |
| Hydrochloric acid prices |
7647-01-0 |
188 |
3.3% |
-6.91% |
1.08% |
| Hydrogen peroxide prices |
7722-84-1 |
600 |
-1.64% |
1.67% |
-9.1% |
| Isopropyl alcohol prices |
67-63-0 |
6,967 |
-2.67% |
1.28% |
4.44% |
| Lithium carbonate prices |
554-13-2 |
148,000 |
2.78% |
2.4% |
-7.05% |
| Methanol prices |
67-56-1 |
2,645 |
-0.56% |
1.83% |
-1.7% |
| Nickel prices |
7440-02-0 |
129,350 |
-0.05% |
-0.79% |
0.96% |
| Phenol prices |
108-95-2 |
8,310 |
-1.25% |
-2.15% |
5.76% |
| Propylene prices |
115-07-1 |
8,451 |
2.42% |
2.19% |
-1.14% |
| Propylene glycol prices |
57-55-6 |
9,200 |
0.36% |
0.86% |
4.12% |
| Sulfur prices |
7704-34-9 |
9,502 |
0.7% |
0.92% |
2.45% |
| Toluene prices |
108-88-3 |
6,717 |
0.75% |
3.39% |
3.52% |
| Urea prices |
57-13-6 |
1,718 |
-0.98% |
-0.8% |
-1.96% |
| Xylene prices |
1330-20-7 |
6,760 |
0.85% |
2.01% |
6.64% |
China's
Basic Chemicals market showed a mixed performance on August 12. Upstream energy and feedstock support helped several products extend gains, while weak downstream purchasing continued to pressure selected solvents and intermediates. Among the strongest movers,
Propylene surged 2.42% day-on-day and
Ethyl Acetate climbed 2.35%, supported by firmer olefin and ester value chains.
Aniline gained 1.72% as benzene-linked production costs remained elevated and downstream polyurethane demand stayed relatively stable.
Ethylene Glycol rose 1.65%, with polyester sector procurement and inventory replenishment providing support. Recent market reports indicate that feedstock cost increases and polyester-related demand have continued to underpin glycol sentiment.
On the downside, solvent markets weakened, led by
Isopropyl Alcohol
(-2.67%),
Hydrogen Peroxide
(-1.64%), and
Dichloromethane
(-1.45%), reflecting cautious downstream consumption and sufficient spot availability.
Acetic Acid
edged down 0.2% and remains under pressure from moderate demand despite fluctuations in methanol feedstock costs. Industry analysis suggests that recent acetic acid pricing has been more influenced by supply conditions than by end-user demand growth.
In battery materials,
Lithium Carbonate
jumped 2.78% to 148,000 CNY/ton, extending its weekly increase to 2.4%. The rebound is linked to tighter supply expectations, inventory normalization, and continued demand from energy storage and electric vehicle sectors. Recent industry reports highlight that lithium markets have recovered from previous oversupply conditions, supported by mine supply disruptions and resilient battery demand, although analysts remain cautious about longer-term supply expansion risks.
Aromatics remained relatively firm, with
Toluene
(+0.75%) and
Xylene
(+0.85%) posting gains, while
Phenol
slipped 1.25%. Recent market developments show that higher crude oil and naphtha costs have continued to support benzene and related aromatic chains, though downstream profitability remains constrained. Overall, the market continues to exhibit a divergence between feedstock-driven strength in selected products and cautious purchasing behavior in downstream chemical sectors.
Fine Chemicals Prices
China's
Fine Chemicals market exhibited significant divergence on August 12, with specialty solvents and polymer intermediates outperforming while selected inorganic and oleochemical products weakened. The standout performer was
Dimethyl Sulfoxide (DMSO), which surged 11.63% day-on-day to 12,000 CNY/ton, marking the strongest gain across the category. The sharp increase is likely associated with tight spot availability, production maintenance at selected suppliers, and improved procurement from pharmaceutical and electronics-related downstream sectors. Despite the strong daily rebound, DMSO remains 3.88% lower on a monthly basis, indicating that the market is recovering from previous oversupply pressure rather than entering a sustained bullish cycle.
Another notable gainer was
PTMEG (Polytetramethylene Ether Glycol)
, rising 2.63% to 19,500 CNY/ton. Market sentiment was supported by relatively stable demand from the spandex industry and expectations of tighter feedstock availability. PTMEG remains a critical raw material for spandex production, with industry reports showing that demand from textile, sportswear, and performance-fabric applications continues to underpin long-term consumption trends. Recent market updates also indicate ongoing monitoring of PTMEG and BDO supply conditions across China's spandex value chain.
On the downside,
Calcium Carbonate
recorded the largest decline, falling 4.0% day-on-day and extending its monthly loss to more than 50%. The sharp correction reflects persistent oversupply, weak construction-material demand, and intense competition among producers. Meanwhile,
Oleic Acid
dropped 2.56% as edible oil and fatty acid markets softened after a strong rally earlier in the quarter. However, monthly gains remain above 15%, suggesting underlying demand from surfactants, lubricants, and personal care applications is still relatively healthy.
Potassium Permanganate
decreased 1.59% and
Melamine
slipped 1.18%, with melamine prices facing pressure from cautious board, laminate, and resin sector purchasing. Market fundamentals remain closely tied to urea feedstock trends, and recent reports indicate that abundant domestic urea supply and elevated inventories continue to limit cost-push momentum for downstream nitrogen-based chemicals.
From an industry perspective, demand recovery remains uneven across fine chemical segments. High-value specialty solvents and polymer intermediates are benefiting from downstream manufacturing activity, while construction-related and commodity fine chemicals continue to face demand headwinds. Overall, the market remains characterized by selective procurement, inventory management, and a growing divergence between specialty chemical products linked to advanced manufacturing and those exposed to traditional industrial sectors.
Energy and Plastics chemicals Prices
China's
Energy and Plastics market remained generally firm on August 12, supported by strengthening crude oil prices and stable downstream industrial demand. The most notable move came from
WTI Crude Oil, which rose 1.22% to USD 83/barrel, extending weekly gains to 3.85%. Recent international energy markets have been supported by ongoing geopolitical tensions in the Middle East, uncertainty surrounding shipping routes in key oil transit corridors, and concerns over potential supply disruptions. Market reports indicate that stalled U.S.-Iran negotiations and continued security risks in the Strait of Hormuz have maintained a geopolitical risk premium in crude oil prices.
Supported by higher crude benchmarks, domestic refined products remained firm.
Gasoline
increased 0.15% day-on-day and has accumulated a strong monthly gain of 6.58%, reflecting seasonal transportation demand and higher refinery pricing. Although recent U.S. crude inventory data showed a significant stock build, gasoline inventories continued to decline, indicating relatively resilient fuel consumption and helping support refined product markets globally.
Asphalt
edged up 0.28% to 4,335 CNY/ton, tracking strength in crude oil and refinery feedstocks. Infrastructure and road construction activity continue to provide underlying demand support, while feedstock costs remain elevated due to volatility in global oil markets. Despite the daily increase, asphalt prices remain slightly lower on a monthly basis, suggesting that downstream construction demand has not fully translated into sustained price momentum.
Within the polymer sector,
ABS
prices rose 0.35% to 9,550 CNY/ton. The improvement was primarily supported by stable costs across the styrene-acrylonitrile-butadiene value chain and steady procurement from home appliance, automotive, and consumer electronics manufacturers. Although weekly and monthly gains remain modest, ABS continues to benefit from relatively balanced supply-demand fundamentals compared with other commodity plastics.
From a broader market perspective, the energy complex remains the primary driver of sentiment across downstream petrochemical and plastics markets. Recent industry forecasts from the International Energy Agency (IEA) highlight ongoing supply-chain disruptions and tighter near-term oil balances despite softer global demand expectations. Elevated crude prices have continued to support refinery margins and petrochemical feedstock costs, providing a bullish cost foundation for fuels, asphalt, and selected polymer products. However, downstream manufacturers remain cautious amid uncertain macroeconomic conditions, resulting in moderate rather than aggressive purchasing activity. Overall, the market is currently characterized by
crude-led cost support, resilient fuel demand, and relatively stable plastics consumption
, with future price direction likely to remain closely linked to developments in global energy markets.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
August 12, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.



 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 3YRS

