Daily Chemical Market Price Overview — August 14, 2026
The latest daily chemical price update highlights significant movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy, and
Plastics. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better track short-term market volatility, supply-demand changes, feedstock costs, and broader pricing trends across the chemical supply chain.
Market focus today centered on sharp rebounds in
Sodium hypochlorite,
Polyvinyl chloride (PVC), and
Lauric acid, while
Poly(ethylene glycol) and selected energy products experienced notable corrections. Upstream crude oil remained elevated despite a daily pullback, while cautious downstream demand and regional supply conditions continued to create significant price differentiation across chemical markets.
Top Price Movers
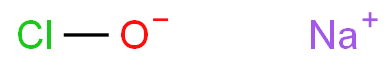
Sodium hypochlorite recorded the strongest daily price increase across all monitored products, surging 34.11% to CNY 519/ton. The sharp rebound appears to reflect a short-term tightening in regional spot availability and quotation adjustments, while chlorine-chain supply conditions and local operating rates remain key price drivers. Despite the strong daily gain, weekly and monthly prices remain down 5.20% and 3.01%, respectively, suggesting that the move is more likely a short-term market correction than a broad-based uptrend.
Polyvinyl chloride (PVC) posted an exceptional 21.90% daily increase to CNY 5,400/ton. However, the simultaneous weekly decline of 2.62% and monthly decline of 1.80% indicate that the move is inconsistent with a broad-based market rally. The unusually large daily change may therefore reflect a regional quotation, benchmark, grade, or data-source adjustment. PVC fundamentals remain influenced by upstream feedstock costs, producer operating rates, inventories, and cautious downstream demand, so the latest spike should be monitored for confirmation in subsequent daily data.
Lauric acid recorded the third-largest daily increase, jumping 17.56% to CNY 15,400/ton. The sharp rebound followed a prolonged decline, with weekly and monthly prices still down 1.89% and 15.63%, respectively. The latest move therefore appears to be a short-term replenishment and quotation adjustment rather than a confirmed trend reversal. Lauric acid prices remain highly sensitive to
palm kernel oil (PKO) costs and downstream demand from personal-care and oleochemical applications.
Price rebounded 17.56% today — Monitor spot availability and feedstock costs before interpreting the move as a sustained uptrend.
Basic Chemicals Prices
| Product |
CAS |
Price (CNY/TON) |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
3,060 |
0.43% |
-2.55% |
-2.41% |
| Acetic anhydride prices |
108-24-7 |
5,213 |
-0.48% |
-0.1% |
-1.56% |
| Acetone prices |
67-64-1 |
6,425 |
-0.59% |
2.15% |
12.31% |
| Acetonitrile prices |
75-05-8 |
8,863 |
0.52% |
-1.17% |
-0.32% |
| Ammonium sulfate prices |
7783-20-2 |
1,137 |
-0.52% |
-1.69% |
-0.77% |
| Calcium carbide prices |
75-20-7 |
2,460 |
1.23% |
1% |
-2.87% |
| Cobalt prices |
7440-48-4 |
326,900 |
-0.24% |
-3.13% |
-9.19% |
| Copper sulfate prices |
7758-98-7 |
27,267 |
-0.49% |
-0.35% |
8.97% |
| Dichloromethane prices |
75-09-2 |
2,098 |
3.71% |
-3.26% |
-0.9% |
| Ethylene glycol prices |
107-21-1 |
5,092 |
-0.16% |
-0.45% |
10.3% |
| Formaldehyde prices |
50-00-0 |
1,241 |
0.89% |
-0.88% |
-2.28% |
| Glycerol prices |
56-81-5 |
9,800 |
4.26% |
-0.38% |
0.33% |
| Hydrogen peroxide prices |
7722-84-1 |
587 |
-2.17% |
0.17% |
-9.85% |
| Isopropyl alcohol prices |
67-63-0 |
6,983 |
-1.41% |
2.94% |
5.18% |
| Lithium carbonate prices |
554-13-2 |
151,000 |
1.34% |
5.37% |
-5.49% |
| Methanol prices |
67-56-1 |
2,708 |
1.5% |
3.46% |
-0.79% |
| Nickel prices |
7440-02-0 |
127,750 |
-0.8% |
-1.45% |
0.26% |
| Phenol prices |
108-95-2 |
8,105 |
-1.22% |
-3.95% |
4.42% |
| Potassium nitrate prices |
7757-79-1 |
4,925 |
-1.5% |
-2.36% |
-1.52% |
| Propylene prices |
115-07-1 |
8,614 |
0.27% |
4.78% |
0.9% |
| Propylene glycol prices |
57-55-6 |
9,100 |
-1.09% |
-0.99% |
3.76% |
| Toluene prices |
108-88-3 |
7,050 |
2.92% |
2.6% |
3.86% |
| Urea prices |
57-13-6 |
1,705 |
-0.47% |
-1.72% |
-2.58% |
Basic chemicals showed a mixed trading pattern, with
Toluene,
Methanol,
Lithium carbonate, and
Dichloromethane posting notable daily gains, while
Glycerol and
Hydrogen peroxide moved in opposite directions across individual markets.
Toluene rose 2.92% to CNY 7,050/ton, supported by firmer upstream energy and aromatics sentiment as well as relatively resilient blending and chemical demand.
Methanol increased 1.50% to CNY 2,708/ton, extending its weekly gain to 3.46%, as stronger feedstock and futures sentiment provided support despite still-cautious downstream procurement. Meanwhile,
Lithium carbonate advanced 1.34% to CNY 151,000/ton and was up 5.37% on the week, reflecting tightening near-term supply and improving downstream battery-material demand. Recent market assessments indicate that concentrated maintenance at lithium-salt producers during July-August has constrained spot availability, while downstream production schedules have continued to improve.
Among the declining products,
Phenol fell 1.22% to CNY 8,105/ton, with its weekly decline reaching 3.95%, indicating continued pressure from weak downstream purchasing and a softer supply-demand balance.
Isopropyl alcohol decreased 1.41% on the day but remained 2.94% higher week on week, suggesting that the recent correction is more of a short-term adjustment after a stronger rebound rather than a complete reversal of market sentiment.
Hydrogen peroxide dropped 2.17% to CNY 587/ton and remained nearly 10% lower on a monthly basis, reflecting persistent oversupply pressure and limited downstream demand. By contrast,
Acetone slipped 0.59% to CNY 6,425/ton but still recorded a 12.31% monthly increase, showing that the recent weakness is occurring after a substantial earlier rally rather than within a prolonged downtrend. Historical market analysis also shows that acetone pricing is highly sensitive to producer inventory, terminal purchasing and factory pricing adjustments.
Upstream-linked products also strengthened selectively.
Calcium carbide rose 1.23% to CNY 2,460/ton, while
Propylene edged up 0.27% and gained 4.78% over the week, pointing to relatively firm upstream feedstock sentiment. Propylene remains an important cost driver for downstream derivatives, although market participants continue to monitor downstream operating rates and purchasing enthusiasm.
Acetic acid increased 0.43% on the day but remained 2.55% lower week on week, while
Acetic anhydride slipped 0.48%, indicating that the acetic-acid chain is still characterized by cautious downstream buying. In contrast,
Ethylene glycol was little changed at CNY 5,092/ton, although its monthly increase of 10.30% indicates that the product remains substantially stronger than its recent daily movements suggest.
Overall, the basic chemicals market remained
highly differentiated rather than uniformly bullish or bearish. Aromatics and selected feedstock-linked products benefited from firmer cost expectations, while products facing weaker downstream demand or ample availability continued to correct. The most notable near-term signal is the strengthening of
Lithium carbonate: its 5.37% weekly increase contrasts with weakness in
Cobalt, which fell 3.13% over the week and 9.19% over the month. This divergence is consistent with a battery-material market increasingly driven by differences in supply constraints and end-use demand; recent industry commentary points to particularly strong growth in stationary energy-storage demand, helping offset softer EV demand.
Fine Chemicals Prices
Fine chemicals showed a highly differentiated trading pattern, led by sharp moves in
Sodium hypochlorite,
Lauric acid,
Cyanuric acid, and
Trichloroethylene, while
Poly(ethylene glycol) recorded a significant correction.
Sodium hypochlorite surged 34.11% to CNY 519/ton, despite remaining 5.20% lower on a weekly basis, suggesting a short-term regional supply or quotation adjustment rather than a broad-based recovery. Sodium hypochlorite pricing is closely linked to chlorine and caustic-soda economics as well as local operating rates, and recent market data showed substantial regional price differences in China, highlighting the sensitivity of this product to local supply-demand conditions.
Cyanuric acid rose 9.68% to CNY 8,500/ton, extending its monthly gain to 8.05%. Its recent strength is consistent with tighter cost conditions in the urea-linked chain and firm demand for chlorine-based water-treatment products; industry commentary has also identified cyanuric acid as a major cost component in trichloroisocyanuric acid production.
Lauric acid recorded the largest percentage increase among the listed products, jumping 17.56% to CNY 15,400/ton, although its weekly and monthly changes remained negative at -1.89% and -15.63%, respectively. The sharp daily rebound therefore appears more consistent with a short-term quotation or replenishment adjustment following a prolonged correction than with a fundamental reversal. Lauric acid is highly correlated with
palm kernel oil (PKO) costs, while downstream demand is concentrated in personal-care applications and remains relatively price-sensitive. Recent Chinese market data showed lauric acid around CNY 18,050/ton in late July, confirming that the product had already experienced substantial price volatility before the latest move.
Melamine, meanwhile, edged down 0.21% to CNY 6,225/ton but remained 4.01% higher on a monthly basis. The market continues to balance relatively weak panel and resin demand against changes in operating rates, while the upstream
Urea market remains under supply pressure, limiting the strength of cost-side support.
Poly(ethylene glycol) was the clearest negative outlier, falling 14.09% to CNY 9,450/ton and turning 2.57% lower on a weekly basis. The magnitude of the decline suggests a significant market quotation adjustment, profit-taking, or a correction after earlier cost-driven gains rather than a simple change in end-user demand. The broader BDO/PTMEG chain has experienced substantial price movement during 2026, while industry reports continue to characterize downstream spandex demand as relatively weak.
PTMEG itself increased 2.63% to CNY 19,500/ton and remained 1.00% higher on the month, indicating that feedstock and supply-side factors are currently providing more support than downstream demand. Recent industry data also showed strong growth in China's BDO exports during the first half of 2026, adding another variable to the domestic BDO/PTMEG supply balance.
Other fine chemicals remained comparatively stable.
Retinol (Vitamin A) increased 1.85% to CNY 55/kg and was up 1.89% week on week, although the monthly change remained negative at -5.36%, pointing to a modest rebound within a still-soft monthly trend.
Sodium metabisulfite was essentially unchanged at CNY 3,993/ton, indicating balanced near-term supply and demand.
Trichloroethylene rose 8.65% to CNY 4,900/ton but remained 0.56% lower for the week and 4.17% lower for the month. Given its volatile regional quotations in China, the latest increase is more likely to reflect short-term supply availability and transaction-price adjustments than a decisive change in the broader market balance. Overall, the Fine Chemicals segment remains characterized by
large short-term price dispersion, selective supply tightening, and corrections after earlier rallies, with cyanuric acid and selected chlorine-chain products showing the strongest near-term momentum, while PEG remains under the greatest correction pressure.
Energy, Rubber, Plastic and other chemicals Prices
Energy and plastics markets showed a mixed pattern, with
PVC and
ABS maintaining a firmer tone while energy products experienced modest corrections.
PVC (Polyvinyl chloride) recorded an exceptionally large 21.90% daily increase to CNY 5,400/ton in the provided dataset, although its weekly and monthly changes remained negative at -2.62% and -1.80%, respectively. This unusual combination suggests that the move may reflect a benchmark, regional quotation, grade, or data-source adjustment rather than a broad-based one-day surge in China's PVC spot market. Public market assessments around August 14 showed PVC quotations generally fluctuating within a relatively narrow range, with supply from major producers remaining stable. Futures sentiment provided some support, but downstream demand remained relatively cautious. Therefore, the latest PVC reading should be interpreted primarily as a
short-term quotation normalization or supply-side repricing signal rather than confirmation of a fundamental 22% market rally.
ABS increased 0.34% to CNY 9,733/ton, extending its weekly and monthly gains to 1.24% and 1.44%. The relatively steady upward trend is consistent with firmer upstream cost conditions across the ABS chain, particularly styrene, butadiene and acrylonitrile, while demand remains selective. Recent market assessments put China's domestic ABS price around CNY 9,400–9,500/ton in mid-August, broadly consistent with the level in the dataset. The global ABS market has also remained sensitive to feedstock costs and regional supply changes, while geopolitical disruptions earlier in 2026 generated a significant cost-driven rally in styrene and butadiene. As a result, the current ABS market is better characterized as
cost-supported consolidation rather than a strong demand-led expansion.
Within the energy complex,
WTI Crude Oil declined 2.41% to USD 81/barrel on the day but remained 3.85% higher on the week and 2.56% higher on the month. The short-term pullback therefore appears to be a correction from elevated levels rather than a decisive bearish reversal. Oil prices have continued to receive a geopolitical risk premium from tensions surrounding the
Strait of Hormuz, where disruptions to tanker traffic have raised concerns about crude and refined-product supply. At the same time, softer global demand expectations and concerns over economic growth have limited the upside. Recent market commentary indicates that the oil market is being pulled in two directions: geopolitical supply risks support prices, while weaker demand and ample inventories constrain the rally. This explains why crude can remain above USD 80/barrel while still experiencing substantial day-to-day volatility.
Gasoline edged down 0.39% to CNY 8,607/ton, but remained 1.34% higher on the week and 6.79% higher on the month, indicating that refined-product prices are still benefiting from the earlier crude-oil and geopolitical premium. The gasoline market has recently shown stronger resilience than crude itself because disruptions to global refining capacity can tighten refined-product balances even when crude prices stabilize. Recent industry reports have highlighted elevated gasoline and diesel crack spreads amid refinery disruptions and constrained refining capacity, suggesting that the downstream fuel market may remain relatively firm even if crude prices undergo short-term corrections.
Asphalt declined 0.35% to CNY 4,330/ton but retained a 0.49% weekly gain, reflecting a relatively balanced market. Asphalt remains closely linked to crude-oil and heavy-feedstock costs, while its demand is strongly influenced by infrastructure and road-construction activity. The current combination of a small daily decline and positive weekly performance suggests that cost support is still present, although downstream purchasing has not generated a strong sustained rally.
Anthracite was the largest negative mover in the energy group, falling 10.00% to CNY 1,575/ton. However, its weekly and monthly changes were only -0.72% and -0.24%, respectively, indicating that the extreme daily movement is more likely related to a quotation or benchmark adjustment than to a sudden fundamental collapse in the coal market. Broader coal benchmarks around mid-August remained comparatively firm, while China's domestic coal market continued to be influenced by inventory levels, industrial demand and regional supply conditions.
Overall, the
Energy and Plastics market remained supported by elevated upstream energy costs and geopolitical risk, but downstream demand was not strong enough to produce a broad-based rally.
WTI Crude Oil and
Gasoline remained firmly above their earlier levels despite daily corrections, while
ABS continued to benefit from relatively stable feedstock costs and balanced supply-demand conditions. The most significant data anomaly was
PVC, where the reported 21.90% daily increase contrasts sharply with both its negative weekly/monthly performance and contemporaneous spot-market quotations. Accordingly, the latest PVC figure should be monitored for possible benchmark or data-definition changes before being interpreted as a genuine market surge. In the near term, the sector is likely to remain driven by the interaction of
geopolitical energy risks, refining constraints, feedstock costs, and cautious downstream demand, rather than by a uniform strengthening across all energy and plastics products.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
August 14, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 1YR

