September 9, 2026 chemical market analysis: Silver iodide fell 25.02%, Dimethyl sulfoxide rose 12.44%, and Anthracite gained 11.11%. Explore key price drivers across Basic Chemicals, Fine Chemicals, Energy, and Plastics.GuideView9 MIN READSeptember 9, 2026
Daily Chemical Market Price Overview — September 9, 2026
The latest daily chemical price update highlights key movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy, and
Plastics. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better track short-term market volatility and broader pricing trends across the chemical supply chain.
Market focus today centered on strong gains in
Dimethyl sulfoxide,
Anthracite, and
Dimethyl carbonate, while
Silver iodide recorded the sharpest decline. Energy-linked products and selected solvents benefited from firmer feedstock costs, supply-side tightening, and pre-holiday procurement, whereas several specialty chemicals and polymer products remained volatile amid uneven downstream demand. Overall, the market continued to show a clear split between cost-driven price increases and corrections in products that had recently experienced significant gains.
Silver iodide recorded the largest daily decline across the tracked markets, falling to CNY 1,804/kg after a sharp correction from recent gains. Despite the steep daily drop, weekly prices remained up 43.98%, indicating that the product is still experiencing exceptionally high short-term volatility rather than a confirmed long-term downtrend. The decline may reflect profit-taking, a reversal in spot-market sentiment, or easing cost expectations following weaker silver prices. However, the available market information does not establish a single confirmed cause for the move.
Price dropped 25.02% today — Monitor volatility closely before making sourcing decisions.
Dimethyl sulfoxide recorded the strongest daily gain among the tracked products, rising to CNY 12,200/ton. Regional quotations had already shown substantial price dispersion, with some producers raising offers while others remained at lower levels. The sharp daily increase therefore appears to reflect rapid spot-market repricing and stronger producer sentiment, potentially supported by tighter short-term availability and active procurement. However, monthly prices remain only 1.44% higher, suggesting that the latest move is more consistent with a short-term adjustment than a fully established long-term uptrend.
Anthracite posted the third-largest daily move, rising to CNY 1,750/ton after a sharp short-term rebound. However, weekly and monthly prices remained down 2.51% and 1.53%, respectively, indicating that the latest increase was more likely a recovery from recent weakness than a confirmed sustained uptrend. The move may reflect a rapid adjustment in local quotations, short-term supply sentiment, or renewed procurement interest, but the available information does not confirm a specific structural supply shortage. The contrast between the strong daily gain and negative medium-term performance highlights the product's current volatility.
Basic chemicals moved broadly higher on September 9, with
Ethyl acetate,
Formaldehyde,
Propylene,
Acetone, and
Formic acid recording the strongest daily gains. The rally was concentrated in energy-linked, solvent, and acetic acid-related chains, rather than reflecting a broad-based recovery in downstream demand.
Methanol rose 3.06% to CNY 3,707/ton, with weekly and monthly gains reaching 7.83% and 23.55%, respectively. Market reports indicated that methanol spot prices increased by CNY 110/ton on the day, while rising power coal prices, relatively tight supply, and pre-holiday procurement provided support. However, methanol was already trading near a one-year high, suggesting that the recent rally may face resistance if downstream buying remains mainly restocking-driven.
Acetic acid and Acetic anhydride increased 1.81% and 1.34% daily, supported by higher methanol costs and firmer producer offers. Shandong Hualu Hengsheng raised its acetic acid price by CNY 50/ton and its acetic anhydride quotation by CNY 60/ton, indicating that the upstream cost increase was being passed through the acetic acid derivatives chain.
Ethyl acetate surged 8.32% daily to CNY 6,317/ton, while regional market reports showed North China producer prices rising by around CNY 110/ton as acetic acid costs strengthened and sellers maintained a bullish stance. The move therefore appears to be driven primarily by cost support and tighter short-term availability, although actual transactions remained subject to negotiation.
Propylene jumped 7.22% daily to CNY 9,884/ton, following producer price increases of CNY 400-800/ton in Shandong. Nevertheless, market assessments still described propylene as range-bound, suggesting that the sharp daily increase reflected stronger producer offers and short-term supply sentiment rather than a confirmed structural improvement in demand.
Acetone, Benzene, Toluene, and Xylene also advanced, consistent with the stronger performance of chemical futures linked to aromatics and energy-related feedstocks. Meanwhile, Acetonitrile declined 7.83% daily to CNY 7,950/ton, indicating a sharp correction after recent gains, although its weekly increase remained 6%.
Ammonium sulfate, Copper sulfate, Lithium carbonate, Nickel, and Cobalt weakened, while Potassium chloride and Phosphoric Acid remained under pressure, showing that the market was still divided across different supply-demand structures.
Overall, the strongest gains were concentrated in products supported by rising feedstock costs, producer price adjustments, and pre-holiday procurement. However, the broader industry backdrop remains cautious: recent research from Sinopec's economics institute suggested that China's 2026 ethylene-equivalent consumption could decline by 8%, indicating that high prices and inventory pressure continue to weigh on apparent demand. The current market therefore appears to be characterized by selective cost-driven inflation and short-term supply tightening, rather than a broad-based recovery in chemical consumption.
Fine chemicals showed a highly differentiated market on September 9, with
Dimethyl carbonate and
Dimethyl sulfoxide recording the strongest gains, while
Silver iodide,
Sodium dodecyl sulfate, and
Trichloroethylene posted sharp declines. The market was characterized by strong short-term repricing in selected solvents and intermediates, alongside corrections in products that had recently experienced significant volatility.
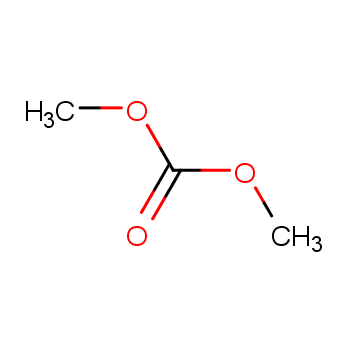
Dimethyl carbonate rose 6.26% daily to CNY 6,500/ton, with weekly and monthly gains reaching 14.41% and 26.36%, respectively. Market reports indicated that DMC prices were supported by production-unit maintenance, reduced operating rates, and tighter availability, while demand from polycarbonate and electrolyte-solvent applications remained relatively firm. Additional support came from pre-holiday procurement and export orders, suggesting that the recent rally was driven by both supply-side constraints and downstream restocking.
Dimethyl sulfoxide surged 12.44% daily to CNY 12,200/ton. Regional quotations reported on September 7-8 showed substantial price dispersion, with some offers rising sharply while others remained at lower levels. This suggests that the current increase may reflect a rapid adjustment in producer offers and spot-market expectations, rather than a fully established long-term trend.
Benzyl alcohol increased 7.25% to CNY 18,500/ton, but its weekly and monthly changes remained negative at -3.38% and -1.12%. The combination of a strong daily rebound and negative medium-term performance indicates a recovery from previous weakness, rather than a confirmed sustained uptrend.
Potassium citrate and Sodium acetate posted modest gains of 1.89% and 0.61%, respectively, while Creatine monohydrate declined 1.56%, suggesting relatively limited momentum in these more specialized markets.
Silver iodide fell 25.02% daily to CNY 1,804/kg, despite remaining up 43.98% on a weekly basis. The sharp reversal is consistent with a highly volatile market undergoing a correction after a strong short-term increase. Silver prices also weakened on September 9, which may have eased cost expectations for silver-containing products, although the available information does not establish a direct causal relationship.
Sodium dodecyl sulfate declined 10.38% to CNY 15,833/ton, following a period of strong gains in regional quotations. The move appears to be a correction after recent price increases, but the specific cause of the daily decline remains uncertain.
Trichloroethylene fell 10.09% to CNY 4,125/ton, while its weekly change remained almost flat, indicating that the latest weakness was more likely a short-term adjustment than a broad monthly downtrend.
Tetrahydrofuran also weakened 1.45% daily and remained down 8.23% monthly, pointing to continued pressure in the downstream polyurethane and specialty-solvent chain.
Overall, the fine chemicals market remains highly selective: DMC is supported by supply tightening and demand from battery-related applications, while DMSO is experiencing rapid spot-market repricing. In contrast, several other products are either correcting after previous gains or remain under pressure from weaker downstream demand. The current market therefore appears to be driven more by product-specific supply-demand changes and short-term procurement behavior than by a broad-based recovery across the fine chemicals sector.
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
September 9, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Energy and plastics markets moved higher on September 9, although the strength was concentrated in energy-linked products and selected polymer chains.
Anthracite recorded the strongest daily gain at 11.11%, while
Asphalt and
Gasoline increased 1.02% and 1.13%, respectively. The market was supported by firmer crude oil prices, higher energy costs, and tighter supply in selected downstream products.
Asphalt rose to CNY 5,423/ton, with weekly and monthly gains reaching 3.67% and 18.03%. Regional spot prices increased across the country, with East China and Southwest China rising by CNY 210/ton and CNY 270/ton, respectively. Market reports attributed the strength to insufficient heavy crude supply, low refinery operating rates, production stoppages, and rapid inventory depletion. The traditional September-October construction season also provided support, although high prices were beginning to limit downstream acceptance.
Gasoline increased 1.13% daily to CNY 9,825/ton, supported by the broader rise in crude oil and energy futures. However, the relatively modest daily increase compared with crude oil suggests that the gasoline market was being supported more by upstream cost expectations than by a sharp improvement in end-user demand.
Anthracite surged 11.11% to CNY 1,750/ton, but its weekly and monthly changes remained negative at -2.51% and -1.53%. This combination indicates a short-term rebound from recent weakness rather than a confirmed sustained uptrend, with the move likely reflecting a rapid adjustment in local quotations or trading sentiment. In plastics,
ABS rose 0.59% to CNY 11,233/ton, with weekly and monthly gains of 2.28% and 12.11%. The product continued to benefit from firmer upstream aromatics and styrene-related costs, but its daily increase was much smaller than the gains seen in upstream chemical futures, suggesting that downstream demand was not expanding at the same pace.
HDPE increased 0.23% to CNY 10,925/ton, while its monthly gain reached 3.4%. The relatively limited daily movement points to a more balanced market, with higher feedstock costs providing support but downstream purchasing remaining cautious.
PVC declined 0.4% daily to CNY 4,930/ton, despite weekly and monthly gains of 4.17% and 8.35%. Regional market data showed that some PVC grades continued to rise on September 9, particularly ethylene-based products in East China, while other grades were stable or only slightly higher. The market was supported by elevated maintenance activity and expectations of seasonal demand recovery, but export restrictions and uneven downstream acceptance limited the pace of further increases.
Overall, the energy market remained driven by crude oil costs and supply-side tightening, with asphalt showing the clearest fundamental strength. Plastics markets were more selective: ABS benefited from stronger upstream costs, HDPE remained relatively stable, and PVC showed signs of consolidation after recent gains. The current market therefore appears to be characterized by strong energy inflation and moderate polymer price recovery, rather than a broad-based acceleration in downstream plastics demand.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 1YR


