Daily Chemical Market Price Overview — October 13, 2026
The post-holiday squeeze has fully reversed.
36 of 90 tracked products moved, and for the second session running the decliners outnumbered the gainers — 22 lower against 14 higher.
Silver iodide prints the largest figure at +33.37% to CNY 2,406/kg, which is a re-basing artefact explained below, and
Carbon Black shows the largest genuine fall at −7.58% to CNY 10,807/ton. The real story is the continued unwinding of the October methanol and glycol squeeze:
Methanol fell another 4.12% to CNY 3,883/ton, taking its two-session loss to 19.9% and its weekly change to −14.63%, while
Ethylene glycol dropped 4.53% to CNY 5,983/ton and
Lithium carbonate lost a further 2.63% to CNY 111,000/ton. Against that,
Chloroform rose 4.80% to CNY 2,533/ton,
Castor oil gained 3.45% to CNY 15,000/ton,
Nickel fell 2.52% to CNY 117,557/ton and
WTI Crude Oil rose 2.17% to USD 94/barrel.
Three forces shaped the day. First, the basket re-expanded from 70 to 90 tracked products as twenty lines returned and none were removed, which restores the speciality coverage lost on October 12 and means comparisons with last Friday are once again meaningful. Second, the crude market turned genuinely two-sided: November WTI settled up 0.43% at
USD 94.14 a barrel, a fresh high since September 24, while December Brent settled
down 0.90% at USD 105.69, as reports that Israel and the United States were discussing a joint strike on Iran before the November 3 midterms pulled against Russia's limited diesel-supply agreement and confirmation that the Strait of Hormuz remains under coalition control. Third, the industrial-gas and glycol complex softened on its own supply logic rather than on cost: Shanxi Lu'an cut its polyester-grade ethylene glycol auction by CNY 120/ton to CNY 5,680/ton on ample north-west supply and weak downstream buying, while methanol's own trend analysis flipped to an explicit downtrend with prices described as sitting at a mid-to-high level with limited upside.

Top Price Movers
Silver iodide shows the largest move in the dataset, rising 33.37% to CNY 2,406/kg from CNY 1,804/kg.
This is a re-basing artefact, not a price move. The line is a returning one: it was tracked at exactly CNY 1,804/kg on September 29 and again on October 9, was absent from the basket on October 10 and October 12, and reappeared today at CNY 2,406/kg. Every previous reading this series has recorded for the product was precisely CNY 1,804/kg, so the re-entry level has been restated rather than the market having re-rated by a third in a single session. The internal evidence confirms it: the weekly change is only plus 16.69% and the monthly plus 23.10%, both of which are inconsistent with a genuine +33.37% daily advance, and no supply or demand event of that magnitude has been reported in the silver-salt market. Silver iodide is a niche specialty used in cloud seeding, photographic chemistry and some pharmaceutical and electrical applications, where volumes are small, quotes are indicative and basket re-entry often resets the reference. Readers should
disregard the 33.37% and treat the level as indicative only until a second consecutive reading establishes a genuine reference.
Heads-up — the 33.37% print is not a market move: silver iodide simply re-entered tracking with a restated reference after being absent on October 10 and 12. Every prior reading was CNY 1,804/kg.
Carbon Black fell 7.58% to CNY 10,807/ton, the largest genuine decline of the session, and unlike the silver-iodide print this one is corroborated by the underlying market. Industry assessments had the carbon black market average at
CNY 10,051/ton, down 8.6% week on week though still 46.27% higher than a year earlier, with output at 109,900 tonnes and the operating rate at 57.41%, both broadly flat. The mechanism is a genuine margin squeeze rather than a demand shock: feedstock cost was CNY 9,224.2/ton, giving a gross profit of −CNY 16.28/ton, heavily negative although improved from −CNY 58.87/ton the previous week. Exports remain the one bright spot, with August volumes at 123,800 tonnes, up 6.05% year on year, while domestic apparent consumption slipped 1.44% to 434,400 tonnes and inventory eased 1.53% to 406,200 tonnes. The caution here is about the
level rather than the direction: the tracked line had been frozen at exactly CNY 11,693/ton for six consecutive sessions through September 29, October 8, 9, 10 and 12, well above the roughly CNY 10,051/ton market average, so part of today's fall is the tracked reference catching down to where the physical market already was. The direction is right and confirmed, but
the 7.58% overstates how much of the move happened today. The one-year price position is in the top band with limited upside, and the outlook is for weak consolidation.
Price dropped 7.58% today — the underlying market confirms an 8.6% weekly fall to about CNY 10,051/ton, but note the tracked line had been stale at CNY 11,693/ton for six sessions, so part of this is a reference catch-down rather than a same-day move.
Methanol fell 4.12% to CNY 3,883/ton, extending a collapse that has now removed
19.9% in two sessions from the October 9 peak of CNY 4,847/ton and left the product 14.63% lower on the week — the worst weekly performance in the basket. The level is now decisively below where it stood on September 22, meaning the entire autumn rally has been given back. The market's own trend assessment flipped explicitly to
“clear decline” with prices characterised as mid-to-high with limited upside. The reversal has been orderly and physical rather than panicked: coastal and river-port assessments led the way down while inland production regions held, sellers cut offers to move cargo, and downstream plants never raised operating rates to validate the earlier spike. October's rally had been built on a Hormuz-linked import squeeze and port inventory draw, and once cargo could move freely again the premium evaporated almost immediately. The futures contract on the Zhengzhou exchange remains far below spot at CNY 3,233/ton, which tells buyers that the market expects the physical level to keep falling toward it.
Procurement advice is unchanged: do not restock on the dip, wait for the basis to stabilise, because spot is still more than CNY 600/ton above the forward curve and that gap is the clearest measure of how much further this can fall.
Price dropped 4.12% today — the autumn rally is fully erased, 19.9% gone in two sessions. Spot at CNY 3,883/ton remains over CNY 600/ton above the futures curve, so further downside should be expected before restocking.
Basic Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
4,860 |
0% |
0.08% |
17.75% |
| Acetic anhydride prices |
108-24-7 |
7,240 |
0% |
0.54% |
9.7% |
| Acetone prices |
67-64-1 |
8,638 |
-0.86% |
1.17% |
0.73% |
| Ammonium nitrate prices |
6484-52-2 |
4,150 |
0% |
0% |
0% |
| Ammonium sulfate prices |
7783-20-2 |
1,260 |
-2.1% |
-2.15% |
6.46% |
| Aniline prices |
62-53-3 |
15,900 |
1.27% |
4.15% |
9.82% |
| Benzene prices |
71-43-2 |
10,501 |
0.32% |
1.23% |
8.92% |
| Borax prices |
1303-96-4 |
6,640 |
0% |
1.05% |
3.99% |
| boric acid prices |
10043-35-3 |
11,600 |
0% |
0% |
0.47% |
| Calcium chloride prices |
10043-52-4 |
1,433 |
0% |
1.42% |
5.36% |
| Calcium phosphate prices |
7758-87-4 |
10,000 |
0% |
0% |
0% |
| Caustic Soda prices |
68988-74-9 |
633 |
0% |
-0.16% |
-0.63% |
| Chloroform prices |
67-66-3 |
2,533 |
4.8% |
2.4% |
6.92% |
| Cobalt prices |
7440-48-4 |
260,700 |
-0.76% |
-0.59% |
-7.98% |
| Dichloromethane prices |
75-09-2 |
3,295 |
0% |
18.53% |
21.96% |
| distilled water prices |
- |
450 |
0% |
0% |
0% |
| Ethanol prices |
64-17-5 |
5,636 |
0% |
0.32% |
1.06% |
| ethyl acetate prices |
141-78-6 |
7,273 |
0.46% |
6.02% |
8.94% |
| Ethylene glycol prices |
107-21-1 |
5,983 |
-4.53% |
-3.5% |
-2.85% |
| Ethylene Oxide prices |
75-21-8 |
9,700 |
0% |
0% |
7.93% |
| EVA prices |
- |
11,333 |
0% |
2.72% |
2.75% |
| Formaldehyde prices |
50-00-0 |
1,950 |
-1.52% |
6.33% |
9.7% |
| Formic acid prices |
64-18-6 |
2,100 |
0% |
2.79% |
-9.9% |
| Heptane prices |
142-82-5 |
16,400 |
0% |
1.23% |
4.05% |
| Hexane prices |
110-54-3 |
10,325 |
0% |
0% |
5.43% |
| Hydrochloric acid prices |
7647-01-0 |
192 |
-1.54% |
1.57% |
3.83% |
| Hydrogen peroxide prices |
7722-84-1 |
713 |
0% |
0% |
3.18% |
| Iodine prices |
7553-56-2 |
640 |
0% |
0% |
0% |
| Lithium carbonate prices |
554-13-2 |
111,000 |
-2.63% |
-6.91% |
-12.14% |
| Methanol prices |
67-56-1 |
3,883 |
-4.12% |
-14.63% |
15.85% |
| Nickel prices |
7440-02-0 |
117,557 |
-2.52% |
-2.97% |
-3.56% |
| PET prices |
- |
8,900 |
-0.78% |
0.35% |
3.58% |
| Phenol prices |
108-95-2 |
9,413 |
-0.13% |
2.73% |
2.93% |
| Phosphoric Acid prices |
7664-38-2 |
8,375 |
0% |
0% |
-0.21% |
| Poly(vinyl alcohol) prices |
9002-89-5 |
10,400 |
0% |
0% |
0% |
| Potassium carbonate prices |
584-08-7 |
7,450 |
0% |
0% |
-0.63% |
| Potassium chloride prices |
7447-40-7 |
3,300 |
-0.51% |
-0.93% |
-0.18% |
| Propane prices |
74-98-6 |
6,150 |
0% |
0% |
0.36% |
| Propylene prices |
115-07-1 |
10,701 |
-0.47% |
6.54% |
4.75% |
| Propylene glycol prices |
57-55-6 |
9,833 |
-1.01% |
4.64% |
0.38% |
| PX prices |
- |
10,500 |
0% |
4.26% |
6.42% |
| Pyridine prices |
110-86-1 |
18,471 |
0% |
0% |
0.18% |
| Sodium bicarbonate prices |
144-55-8 |
1,208 |
0.67% |
0.33% |
-0.17% |
| Sodium fluoride prices |
7681-49-4 |
4,100 |
2.5% |
0% |
-1.18% |
| Sodium hydroxide prices |
1310-73-2 |
2,570 |
0% |
0.12% |
1.1% |
| Sodium sulfate prices |
7757-82-6 |
560 |
0% |
0% |
0% |
| Sulfur prices |
7704-34-9 |
7,179 |
-1.91% |
-4.2% |
-5.77% |
| sulfuric acid prices |
7664-93-9 |
1,678 |
0% |
-1.06% |
-5.14% |
| Titanium dioxide prices |
13463-67-7 |
14,260 |
0.28% |
0.14% |
0.46% |
| Toluene prices |
108-88-3 |
8,983 |
0% |
1.95% |
6.65% |
| Urea prices |
57-13-6 |
1,735 |
-1.31% |
-1.58% |
0.06% |
| White cement prices |
- |
450 |
0% |
0% |
0% |
| White phosphorus prices |
12185-10-3 |
28,396 |
0% |
2% |
0.24% |
| Xylene prices |
1330-20-7 |
8,777 |
0% |
1.98% |
2.05% |
| Zinc chloride prices |
7646-85-7 |
11,825 |
0% |
0% |
0% |
Basic chemicals saw
23 of 55 tracked products move, 7 higher and 16 lower — the widest negative skew of any segment and a clear reversal from the cost-push pattern of last week. The gains were led by
Chloroform up 4.80% to CNY 2,533/ton,
Sodium fluoride up 2.50% to CNY 4,100/ton,
Aniline up 1.27% to CNY 15,900/ton,
Sodium bicarbonate up 0.67% to CNY 1,208/ton,
ethyl acetate up 0.46% to CNY 7,273/ton,
Benzene up 0.32% to CNY 10,501/ton and
Titanium dioxide up 0.28% to CNY 14,260/ton. The declines were broad and steep:
Ethylene glycol down 4.53% to CNY 5,983/ton,
Methanol down 4.12% to CNY 3,883/ton,
Lithium carbonate down 2.63% to CNY 111,000/ton,
Nickel down 2.52% to CNY 117,557/ton,
Ammonium sulfate down 2.10% to CNY 1,260/ton,
Sulfur down 1.91% to CNY 7,179/ton,
Hydrochloric acid down 1.54% to CNY 192/ton,
Formaldehyde down 1.52% to CNY 1,950/ton,
Urea down 1.31% to CNY 1,735/ton and
Propylene glycol down 1.01% to CNY 9,833/ton.
Ethylene glycol was the day's second-largest genuine decline and it is a supply story, not a cost story. The product fell 4.53% to CNY 5,983/ton, with the polyester-grade benchmark down 4.74% to CNY 5,983.33/ton. The trigger was visible and specific:
Shanxi Lu'an cut the reserve price on its 500-tonne polyester-grade auction by CNY 120/ton to CNY 5,680/ton for delivery at Shouyang, with acceptance terms CNY 50/ton higher. That is a mainstream north-west producer actively discounting to clear inventory, and the market read it exactly as intended — as evidence of ample regional supply against weak downstream buying appetite. Glycol's position is the mirror image of methanol's: both products rallied earlier in October on logistics disruption, both have now unwound, and both are being led down by producers in the north-west who would rather discount than hold. Diethylene glycol fell even harder at 5.47%, which confirms this is a whole glycol-chain repricing rather than a single-grade event.
The tracked level of CNY 5,983/ton is the lowest since September 28, and with regional supply still ample the risk remains lower.
Chloroform produced the segment's best gain, up 4.80% to CNY 2,533/ton, and it is a genuine move that extends the chloromethane firmness seen in dichloromethane over the past week. The two products share feedstock and often move together, so the chloroform jump is best read as the same producer-discipline dynamic that drove dichloromethane up 18.53% on the week now spreading to the sister grade. Chloroform also entered the session low on the month, with the monthly change only plus 6.92% before today, so there was room to move.
Sulfur extended its correction, down 1.91% to CNY 7,179/ton and now 4.20% lower on the week, converging toward the benchmark's CNY 7,179/ton; the product remains extraordinarily elevated year on year at roughly 169% above the year-earlier level, so this is a normalisation from an extreme rather than a collapse.
Lithium carbonate slid a further 2.63% to CNY 111,000/ton, its eighth consecutive decline, with the industrial grade down 2.70% to CNY 108,000/ton and industrial lithium hydroxide off 2.15% to CNY 91,000/ton; the battery grade is now 51.92% higher than a year ago but has fallen 17.2% from the CNY 134,000/ton level of September 22.
Nickel fell 2.52% to CNY 117,557/ton and the fall is part of a broader non-ferrous retreat that has become the clearest counterweight to the chemical rally — zinc eased 1.29%, silver 1.80% and antimony 1.94% on the same session, and non-ferrous metals have been the weakest large sector for several days.
Propylene slipped 0.47% to CNY 10,701/ton, its first decline after two strong sessions, though it remains 6.54% higher on the week; the pause after the Shandong producer increases of October 10 and 12 is a natural consolidation rather than a reversal.
Aniline rose 1.27% to CNY 15,900/ton, holding above the CNY 15,700/ton producer levels set on October 10 and now 9.82% higher on the month, which makes it one of the few products to have sustained its October gains.
Formaldehyde eased 1.52% to CNY 1,950/ton but remains 6.33% higher on the week, a modest give-back after the strong producer-led advance. Among the unchanged lines,
Acetic acid held at CNY 4,860/ton,
PX at CNY 10,500/ton,
Caustic Soda at CNY 633/ton,
Ethylene Oxide at CNY 9,700/ton,
Cobalt at CNY 260,700/ton,
Phenol at CNY 9,413/ton,
Heptane at CNY 16,400/ton,
White phosphorus at CNY 28,396/ton,
Sulfuric acid at CNY 1,678/ton and
boric acid at CNY 11,600/ton.
The overall read for Basic Chemicals is that
the segment has rotated decisively from a cost-push rally into a supply-led correction. Propylene, aniline, formaldehyde and PX are all holding the gains they made on genuine producer action last week, but the products that rallied on logistics and inventory squeezes — methanol, ethylene glycol, sulfur, lithium — are now unwinding those gains as cargo moves freely and north-west producers discount to clear. That is a healthier structure than a uniform rally, because it separates products with real scarcity from those that only had a temporary bottleneck. The immediate watch item is whether the methanol and glycol declines stabilise above their futures levels: until they do, the rest of the oxygenate and glycol complex will keep drifting lower, and the buyers' market in those two grades will persist.
Fine Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Benzyl alcohol prices |
100-51-6 |
18,500 |
0% |
0% |
0.45% |
| Castor oil prices |
8001-79-4 |
15,000 |
3.45% |
1.72% |
1.65% |
| chlorine tablets prices |
- |
8,500 |
0% |
0% |
0% |
| Citric acid prices |
77-92-9 |
6,200 |
0% |
0% |
0% |
| Creatinine prices |
60-27-5 |
300,000 |
0% |
0% |
0% |
| dimethyl carbonate prices |
616-38-6 |
6,033 |
-0.56% |
-0.51% |
-4.05% |
| Dimethyl sulfoxide prices |
67-68-5 |
12,075 |
-1.02% |
4.45% |
3.85% |
| Ferric chloride prices |
7705-08-0 |
2,813 |
0.18% |
0.11% |
0.07% |
| glycolic acid prices |
79-14-1 |
13,000 |
0% |
0% |
0% |
| Guar gum prices |
9000-30-0 |
15,500 |
0% |
0% |
0% |
| Hydroquinone prices |
123-31-9 |
30,500 |
0% |
0% |
0% |
| Lactic acid prices |
50-21-5 |
8,288 |
1.53% |
0.77% |
0.68% |
| Magnesium glycinate prices |
14783-68-7 |
29,000 |
0% |
0% |
0% |
| Melamine prices |
108-78-1 |
6,300 |
-0.21% |
-0.32% |
1.07% |
| Melatonin prices |
73-31-4 |
850 |
0% |
0% |
0% |
| Oleic acid prices |
112-80-1 |
10,000 |
0% |
0% |
0% |
| Potassium permanganate prices |
7722-64-7 |
15,500 |
0% |
0% |
0% |
| Potassium sorbate prices |
24634-61-5 |
15,100 |
0% |
-15.64% |
5.32% |
| Silver iodide prices |
7783-96-2 |
2,406 |
33.37% |
16.69% |
23.1% |
| sodium acetate prices |
127-09-3 |
5,629 |
0% |
1.3% |
1.37% |
| Sodium hypochlorite prices |
7681-52-9 |
553 |
0% |
0% |
0% |
| Sodium metabisulfite prices |
7681-57-4 |
3,903 |
0% |
-0.08% |
-1.04% |
| Triclopyr prices |
55335-06-3 |
47,500 |
0% |
0% |
0% |
| Water softener salt prices |
- |
967 |
0% |
0% |
0% |
| Xanthan gum prices |
11138-66-2 |
21,000 |
0% |
0% |
0% |
Fine chemicals returned to meaningful coverage with
25 products tracked and 7 movers, 4 higher and 3 lower.
Silver iodide shows the largest figure at plus 33.37% to CNY 2,406/kg but that is the re-basing artefact explained in the cards above. Setting it aside, the genuine gains were
Castor oil up 3.45% to CNY 15,000/ton,
Lactic acid up 1.53% to CNY 8,288/ton and
Ferric chloride up 0.18% to CNY 2,813/ton, while
Dimethyl sulfoxide fell 1.02% to CNY 12,075/ton,
dimethyl carbonate lost 0.56% to CNY 6,033/ton and
Melamine eased 0.21% to CNY 6,300/ton.
Castor oil rose 3.45% to CNY 15,000/ton, the largest genuine specialty gain, and it is a clean, isolated move: the product had been pinned at exactly CNY 14,500/ton since it first appeared in the basket on September 28 and has now stepped up to a new reference, with weekly and monthly changes of plus 1.72% and plus 1.65% that are consistent with the daily figure. Castor oil is an agricultural derivative whose pricing tracks the Indian and Brazilian harvest and the ricinoleic acid and sebacic acid complex, and specialty vegetable oils have been firming globally on bio-based chemical demand.
Lactic acid added 1.53% to CNY 8,288/ton, its first movement in many sessions and a return to roughly the September 28 level after a period of drift.
Dimethyl sulfoxide eased 1.02% to CNY 12,075/ton, a small give-back after the sharp step up from CNY 10,850/ton to CNY 12,200/ton during the October 11 session; the product is still 4.45% higher on the week and the consolidation is normal after such a jump.
dimethyl carbonate lost 0.56% to CNY 6,033/ton, continuing to follow methanol lower as its principal feedstock weakens, and it is now 4.05% lower on the month — the clearest example in the segment of methanol's collapse transmitting downstream.
The returning lines are worth noting because their first readings should not be read as price movement. Twenty products re-entered tracking this edition, including
Benzyl alcohol at CNY 18,500/ton,
Guar gum at CNY 15,500/ton,
Xanthan gum at CNY 21,000/ton,
Potassium permanganate at CNY 15,500/ton,
Potassium sorbate at CNY 15,100/ton,
Triclopyr at CNY 47,500/ton,
Melatonin at CNY 850/kg,
Magnesium glycinate at CNY 29,000/ton,
Creatinine at CNY 300,000/ton and
chlorine tablets at CNY 8,500/ton, plus
distilled water at CNY 450/ton and
Calcium phosphate at CNY 10,000/ton in the basic segment, all of which opened flat and should be treated as indicative only. The rest of the segment was unchanged:
Citric acid at CNY 6,200/ton,
sodium acetate at CNY 5,629/ton,
Hydroquinone at CNY 30,500/ton,
Oleic acid at CNY 10,000/ton,
glycolic acid at CNY 13,000/ton,
Sodium hypochlorite at CNY 553/ton,
Sodium metabisulfite at CNY 3,903/ton and
Water softener salt at CNY 967/ton.
The practical message for fine-chemicals buyers is that
the segment is calm but no longer inert. With coverage restored to twenty-five products, the picture is one of a stable contract-priced core and a handful of small, credible moves. Only two items require attention:
dimethyl carbonate, where the methanol collapse is actively pulling prices lower and buyers should expect further weakness, and
dimethyl sulfoxide, where the earlier step change has left the level 12.4% higher than a week ago even after today's small decline. Everything else is holding, and there is no urgency to act on the specialty book.
Energy, Rubber, Plastic and other chemicals Prices
Energy, Rubber, Plastic and other chemicals tracked
10 products, of which
6 moved — 3 higher and 3 lower.
WTI Crude Oil rose 2.17% to USD 94/barrel,
ABS added 0.84% to CNY 12,017/ton and
HDPE gained 0.80% to CNY 11,088/ton, while
Carbon Black fell 7.58% to CNY 10,807/ton,
Asphalt eased 0.29% to CNY 6,240/ton and
Gasoline slipped 0.14% to CNY 10,014/ton.
Carbon at CNY 12,500/ton,
Silica at CNY 6,400/ton,
Basalt at CNY 650/ton and
Poly(vinyl acetate) at CNY 12/kg were unchanged.
WTI Crude Oil was marked at USD 94/barrel in the tracked basket on a reported gain of 2.17%, and the physical settlements confirm the upward revision while revealing the divergence beneath it: November WTI settled at
USD 94.14 a barrel, up 40 cents or 0.43% and the highest close since September 24, while December Brent settled at
USD 105.69, down 96 cents or 0.90%. The two benchmarks moving in opposite directions on the same day is the single most informative signal of the session. The upside pressure came from reports that Israeli Prime Minister Netanyahu and President Trump had discussed a joint strike on Iran before the November 3 midterm elections and even before Israel's own October 27 election, with both the Israeli Defence Forces and United States Central Command reported to be at high readiness; the same day brought 104 Saudi air strikes on Houthi-controlled areas of Yemen and a public accusation by President Trump that the Houthis were deliberately pushing oil higher before the midterms. The downside came from Russia's diesel agreement, which on the disclosed volumes amounts to only about 100,000 barrels a day in October and 125,000 in November against Russian exports of roughly 800,000 barrels a day last year, and from CENTCOM's statement that the Strait of Hormuz is under coalition control with more than 19 million barrels of crude escorted through in a single day. OPEC's monthly report added a longer-horizon note, raising its 2027 demand growth forecast for a sixth consecutive month to 2.55 million barrels a day while cutting its 2026 forecast to just 180,000 barrels a day. The forward curve is where the tension shows most clearly: 2027 WTI futures notched a record high for a twelfth consecutive session at USD 84 a barrel, and 2027 Brent set a fourth straight record at USD 90, which means the market is pricing persistent future scarcity even as the front month chops sideways.
The polymers edged higher again, extending the cost-push that has now run for a week.
ABS rose 0.84% to CNY 12,017/ton and is 3.59% higher on the week, while polystyrene in the physical market jumped 4.40% to lead the rubber-and-plastics board, and nitrile rubber added 2.15%.
HDPE gained 0.80% to CNY 11,088/ton for a 4.30% weekly advance; the wider polyolefin complex was mixed on the day, with LLDPE up 0.33% to CNY 9,950/ton and PP raffia up 0.16% to CNY 10,583.33/ton, so the impulse is still positive but clearly losing momentum.
PVC fell 1.36% to CNY 4,765/ton as the construction-linked grades continued to lag the rest of the polymer complex, and
PET slipped 0.79% to CNY 8,899.58/ton, tracking the weaker polyester chain.
Asphalt eased 0.29% to CNY 6,240/ton. The read is that
the polymer rally is now concentrated in the packaging and engineering grades — HDPE, ABS, PS — while the construction and polyester-linked grades have turned down, which is a more selective and therefore more sustainable pattern than the uniform advance of a week ago.
Overall, the Energy, Rubber, Plastic and other chemicals segment captures the shift that has taken hold since Friday:
crude is chopping sideways at a high level with a widening Brent–WTI spread, polymers are holding their gains but narrowing in breadth, and the one sharp decline is a margin-driven correction in carbon black rather than a demand event. The near-term risk is two-sided and unusually balanced. If a strike on Iran materialises before the November 3 midterms, the front-month crude premium will reassert itself and drag the whole petrochemical chain up with it, as it did last week. If instead the Hormuz escort programme continues to normalise and the Russian diesel volumes reach the market, the pressure that has held polymers and aromatics at these levels will fade, and the products that rallied on temporary bottlenecks — methanol, glycol, sulfur — will keep unwinding. For buyers, the sensible posture is to secure contract volumes on the grades where producer discipline is real and physical scarcity is documented, and to stay short-dated and price-flexible on everything that rallied only because cargo could not move.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
October 13, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.



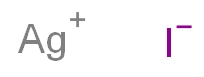
 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 3YRS

