Daily chemical market prices on September 7, 2026: Potassium sorbate plunged 24.50%, Ammonium chloride surged 12.66%, and Anthracite fell 10.00%, highlighting sharp divergences across chemical markets.GuideView11 MIN READSeptember 7, 2026
Daily Chemical Market Price Overview — September 7, 2026
The latest daily chemical price update highlights key movements across major sectors including
Basic Chemicals,
Fine Chemicals,
Energy,
Plastics, and
Rubber. This report summarizes daily, weekly, and monthly price fluctuations to help manufacturers, traders, and procurement professionals better track short-term market volatility and broader pricing trends across the chemical supply chain.
Market focus today centered on
sharp corrections in Potassium sorbate and Anthracite, alongside continued strength in
Dimethyl carbonate, Asphalt, and Carbon Black. Energy and petrochemical markets remained supported by higher crude oil prices and geopolitical risk, while selected chemical products continued to benefit from tighter supply and firm upstream costs.
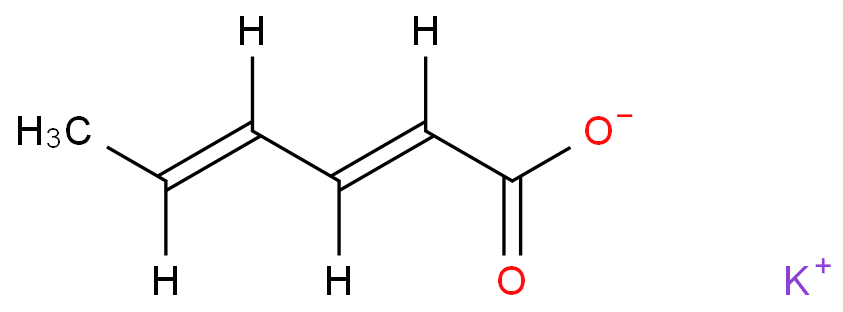
Potassium sorbate recorded the largest daily decline across all four markets, falling from CNY 20,000/ton to CNY 15,100/ton. Despite the sharp correction, monthly prices remain 26.49% higher, indicating that the market is adjusting after a substantial earlier rally. The move may reflect short-term quotation normalization, profit-taking, or a temporary improvement in spot availability. However, the absence of weekly gains suggests that the latest decline should be monitored for confirmation rather than immediately interpreted as a long-term downtrend.
Price dropped 24.5% today — Potential sourcing opportunity, but buyers should confirm whether the correction reflects a sustained change in supply conditions.
Ammonium chloride posted the strongest daily gain among the major chemical products, rising from CNY 790/ton to CNY 890/ton. The sharp increase was likely driven by short-term supply tightness and active replenishment in the fertilizer market, although weekly prices remained unchanged. The divergence between the daily surge and flat weekly performance suggests that the move may be concentrated in selected transactions or regional quotations. Market participants should therefore watch whether higher prices are sustained across the broader market.
Anthracite recorded the largest daily decline in the Energy market, falling from CNY 1,750/ton to CNY 1,575/ton. The sharp correction contrasted with the broader strength in crude oil and asphalt, highlighting the divergence between petroleum-linked and coal-based energy products. Weekly prices were down 5.97%, while monthly prices remained only 1.35% lower, suggesting that the latest move may reflect short-term demand weakness, regional supply pressure, or a rapid adjustment in coal-market quotations.
Price dropped 10.0% today — Buyers may benefit from lower offers, but the market remains sensitive to coal demand and regional supply conditions.
Basic chemicals remained broadly firm, with
Acetic acid, Acetic anhydride, Acetone, and Methanol continuing to strengthen amid tighter supply and firming upstream costs.
Acetic acid rose 2.16% on a daily basis and 4.54% weekly, supported by low producer inventories and continued supplier price increases.
Methanol increased 1.04% daily, extending its monthly gain to 21.13%, as port destocking, tight inland availability, and reduced import expectations linked to Middle East disruptions supported the market. Meanwhile,
Formaldehyde and
Urea posted further gains, with formaldehyde benefiting from higher methanol costs and supply-side maintenance, while urea remained supported by low production, firm coal costs, and stronger export expectations. :contentReference[oaicite:1]{index=1}
Among other notable movements,
Ammonium chloride surged 12.66% daily, while
Copper sulfate gained 5.68% and
Formic acid rose 4.55%, reflecting stronger short-term procurement and supply tightness in selected segments.
Ethylene glycol remained elevated, with monthly gains reaching 18.45%, supported by port inventory drawdowns and tighter spot availability.
Hexane and
Hydrochloric acid also posted notable daily increases, while
Potassium chloride and
Sulfuric acid edged higher. The broader market continued to show divergence, with several products holding at high levels despite mixed downstream demand.
On the weaker side,
Propylene glycol declined 6.70% daily,
Propane fell 5.38%, and
Sulfur dropped 5.06%, indicating short-term pressure in selected feedstock and commodity chains.
Propylene also declined 3.57%, while
Lithium carbonate fell 4.67% daily and 6.10% weekly, suggesting continued adjustment in the battery-materials segment.
Dichloromethane,
Phenol, and
Toluene also softened, although most of these products remained above their recent monthly levels.
Overall, the market remained supported by
firm upstream costs, supply-side constraints, and selective replenishment demand, but price performance continued to diverge across product chains.
Methanol, Ethylene glycol, Acetic acid, Formaldehyde, and Urea remained among the stronger performers, while
Propylene glycol, Propane, Sulfur, and Lithium carbonate faced more pronounced short-term corrections. The latest industry commentary suggests that methanol prices are being supported by port destocking and tighter import availability, while urea remains influenced by low operating rates, firm coal costs, and export expectations. :contentReference[oaicite:2]{index=2}
Fine chemicals showed a highly differentiated market, with
Dimethyl carbonate, Potassium citrate, and Creatine monohydrate among the notable gainers, while
Potassium sorbate and
Trichloroethylene recorded sharp corrections.
Dimethyl carbonate rose 2.36% daily, extending its weekly and monthly gains to 8.30% and 22.33%, respectively, supported by tighter spot availability, production-unit maintenance, and firm demand from electrolyte-solvent and polycarbonate applications. Meanwhile,
Potassium citrate increased 5.12% daily, and
Creatine monohydrate gained 2.44%, although both remained relatively stable on a weekly basis. Overall, the market continued to be driven more by product-specific supply conditions and short-term procurement activity than by broad-based downstream demand.
Dimethyl carbonate remained the strongest representative product in the segment, with its price rising from CNY 5,683/ton to CNY 5,817/ton. Recent market reports attributed the continued rally to
production-unit maintenance, reduced operating rates, limited spot availability, and stronger demand from electrolyte solvents and polycarbonate. Additional support came from pre-holiday restocking and export orders, which diverted part of the supply from the domestic market. The latest industry commentary also pointed to continued producer price increases and tight spot inventory, suggesting that the recent strength was not solely a short-term rebound. However, the pace of gains has been rapid, so the market remains sensitive to the return of supply and the sustainability of downstream procurement.
Among other notable movements,
Potassium citrate rose 5.12% daily to CNY 8,725/ton, while
Creatine monohydrate increased 2.44% to CNY 21,000/ton. These gains suggest stronger short-term procurement or product-specific supply tightness, but the absence of weekly gains indicates that the moves should not yet be interpreted as a broad-based upward trend.
Imidazole also edged higher by 1.16%, while
Ferric chloride and
Sodium acetate remained broadly stable. The overall pattern suggests that downstream buyers were selectively replenishing rather than increasing purchases across the entire fine chemicals sector.
On the weaker side,
Potassium sorbate declined 24.50% daily to CNY 15,100/ton, despite remaining 26.49% higher on a monthly basis. The sharp decline is more consistent with a
short-term correction after an earlier price surge than with a confirmed deterioration in the broader market. Public market information had previously shown strong price increases in potassium sorbate, but the available evidence does not yet establish a specific new production disruption or demand shock behind the latest move.
Trichloroethylene also fell 7.84% daily to CNY 4,700/ton. Earlier September market reports showed significant regional price dispersion and supply-side repricing, with maintenance and reduced operating rates supporting higher offers. The latest decline therefore appears to reflect
high-level price adjustment and regional quotation normalization, although supply availability should continue to be monitored.
Overall, the Fine Chemicals market remained characterized by a
two-speed structure. Supply-sensitive products such as
Dimethyl carbonate continued to strengthen, while most traditional acids, salts, and water-treatment chemicals remained unchanged.
Potassium sorbate and
Trichloroethylene experienced sharp corrections, highlighting the volatility of products that had recently undergone rapid repricing. The near-term outlook remains mixed: products with sustained supply-side support may continue to trade firmly, while products without a clear catalyst are more likely to remain range-bound or experience further short-term corrections. Buyers are therefore likely to remain more active in securing products with tight availability, while taking a more cautious approach toward products with adequate inventories.
Energy, Rubber, Plastic and other chemicals Prices
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
September 7, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.



 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News


 3YRS

