Daily Chemical Market Price Overview — October 16, 2026
The selling pressure eased into a freeze.
35 of 106 tracked products moved, and the balance stayed negative — 6 higher against 29 lower, close to the same ratio as Friday, but with two-thirds of the basket not moving at all. The front of the board belonged to the bulls for the first time this week:
polyvinyl chloride jumped
3.49% to CNY 5,040/ton and
WTI Crude Oil surged
3.16% to USD 98/barrel as the Hormuz escalation drove the physical settlement back above USD 100. Against them,
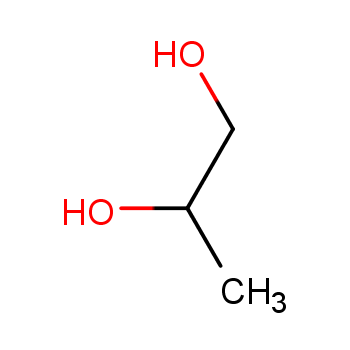
Propylene glycol fell
3.62% to CNY 9,317/ton, the deepest genuine chemical decline of the session,
Lithium carbonate lost a further 2.88% to CNY 101,000/ton for a
thirteenth consecutive decline, and
Cobalt and
Nickel fell 2.12% and 1.43% to CNY 248,800/ton and CNY 117,383/ton. One honesty note up front: unlike Friday’s edition, this one
does carry two returning-line artefacts.
Potassium sorbate printed a 24.5% fall and
Anthracite a 10.0% fall, and both are reversions of anomalous October 15 quotes rather than genuine new declines — they are excluded from all headline analysis below.
Three forces shaped the day. First, the basket expanded again, from 79 to 106 tracked products, as a net twenty-seven lines returned — including the whole artefact-prone group (silver iodide, mineral oil, PTMEG, potassium sorbate, castor oil), which is why the caveat above is needed; measured against October 9 the potassium sorbate print is 11.08% lower and anthracite only 1.87% lower, confirming the double-digit daily percentages were largely one bad base-day quote unwinding. Second, crude exploded on geopolitics: a second consecutive tanker was found burning inside the Hormuz exclusion zone, at least nine vessels have been struck since October 11, transit volumes are down to about 70% of pre-war throughput, missiles aimed at the Saudi bypass terminal of Yanbu were intercepted, and
NYMEX November WTI settled up 3.51% at USD 101.41, back above the 100 dollar mark for the first time in a month, while Brent touched 110 for the first time since May. Third, the battery chain broke its floor: lithium carbonate futures closed at
96,320 yuan, down 4.20% at a new year-to-date low after losing the 100,000 round number on an 18.88% weekly collapse, and the two lithium hydroxide grades — industrial minus 6.82%, battery grade minus 5.88% — took the two worst slots on the day’s chemical board.

Top Price Movers
Polyvinyl chloride rose 3.49% to CNY 5,040/ton from CNY 4,870/ton, the largest genuine move of the session and a complete inversion of the previous session’s story. The line had been 5.76% lower on the week and was sold hard on Thursday because its carbide cost anchor was weakening; today carbide fell
again — calcium carbide was marked down 0.78% to CNY 2,560/ton with the Wuhai trade market reported at CNY 2,450/ton — and PVC rose anyway, which is the tell:
the driver has shifted from cost to supply. Operating rates sit at multi-year lows (61.5% on the wider sample, 66.1% on the narrower one), carbide-route producers are losing CNY 492–866 per tonne, ethylene-route utilisation was cut a further 0.45–3.33 percentage points as feedstock CFR China held near USD 1,130/ton, and October maintenance plans expanded. Social inventory kept de-stocking through the month even though the absolute level (1.043–1.065 million tonnes) is still high. Spot confirmed the bounce: Guangzhou five-type material rose 20–30 yuan to CNY 4,930–4,960/ton, Hangzhou prices turned up intraday from morning weakness, and the futures contract recovered near 4,850 on short-covering while the top-20 seats still hold a net short position. Note the split inside the basket: the second, plain PVC line stayed flat at CNY 4,780/ton — this is a
supply-cut rebound at the top of the curve, not a lift across the complex, with downstream utilisation at 40.2% and still slipping.
Price rose 3.49% today — the largest genuine move of the session, and it happened
despite calcium carbide falling a further 0.78% to CNY 2,560/ton, so cost support is not the story. The rebound is supply-led: multi-year-low operating rates, deep producer losses, October maintenance and continued de-stocking. The flat second PVC line at CNY 4,780/ton shows how narrow the move is.
WTI Crude Oil rose 3.16% to USD 98/barrel in the tracked basket, and the physical settlement was even stronger:
NYMEX November WTI gained USD 3.44 to settle at USD 101.41, up 3.51%, closing above the 100 dollar mark for the first time in nearly a month, while ICE December Brent rose 3.72% to USD 109.86 and briefly topped 110 intraday, its highest level in five months. The escalation is running on three tracks at once. In the Strait of Hormuz, Iran’s navy said its teams found a
second consecutive tanker burning inside the exclusion zone on October 16; at least nine vessels have been struck since October 11, a Singapore-flagged container ship was sunk on October 14, and Kpler put Hormuz flows in the week to October 14 at 9.4 million barrels a day, roughly
70% of pre-war throughput. Saudi Arabia intercepted missiles headed for Yanbu, the Red Sea export terminal that is the pipeline bypass around Hormuz — the market’s standard answer to “what if the strait closes” is now itself under fire. And the inventory support is real, not narrative: EIA commercial crude fell
8.56 million barrels against an expectation of a small build, a near 8.7-million-barrel miss, as hurricane disruption cut Gulf output roughly 300,000 barrels a day while refinery runs rose to 93.5%. Eurasia Group raised its probability of a broader Gulf conflict from 35% to 65% the same day. The offsets are known: the US is offering 17 million barrels from the Strategic Petroleum Reserve, IEA members agreed on October 15 to accelerate more than 20 million barrels of diesel, gasoline stocks actually
built 3.52 million barrels, and the Russian diesel deal is unravelling under bipartisan congressional pressure even as Ukraine resumes strikes on Russian refineries. Crude is now up 69.38% year on year, though the tracked line is still 3.16% below its month-start.
Price rose 3.16% today — and the physical settlement was stronger still at USD 101.41 (+3.51%), back above 100 on a second Hormuz tanker fire, missiles intercepted at the Yanbu bypass, a 8.56-million-barrel EIA drawdown and war-risk odds upgraded to 65%. Reserve releases and a gasoline build are the counterweights; on the month the tracked line is still negative.
Propylene glycol fell 3.62% to CNY 9,317/ton from CNY 9,667/ton, the deepest genuine chemical decline of the session. The benchmark corroborates it almost to the yuan: the industrial reference printed CNY 9,316.67 on October 16 against CNY 9,933.33 a week earlier, a 6.21% weekly fall, and PG ranked the day’s third-worst chemical on the board behind industrial lithium hydroxide (minus 6.82%) and battery-grade lithium hydroxide (minus 5.88%). The position in the chain explains the move: PG sits under propylene oxide, whose own benchmark eased 2.59% on the week to CNY 11,300/ton, while unsaturated-resin and polyester buyers are on hand-to-mouth purchasing; the basket’s propylene feedstock slipped only 0.16% and is still 6.29% higher on the week, so this is a
middle-of-the-chain margin unwind, not a commodity collapse. Two calibration points argue against over-reading it: PG finished the session
1.42% above its October 9 level and 0.02% above its September 16 level — effectively dead flat on the month. In other words, today’s markdown retraces the early-October squeeze rather than breaking any new low. For buyers of UPR resins and coolant blends the practical read is that the discount on offer is real but temporary, and the negotiating window is this week, not next quarter.
Price dropped 3.62% today — the deepest genuine chemical fall of the session, confirmed to the yuan by the benchmark at CNY 9,316.67. But PG ended 1.42% above its week-ago level and 0.02% above its month-ago level: the early-October squeeze is unwinding, a trend has not broken.
Basic Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Acetic acid prices |
64-19-7 |
4,810 |
0% |
-0.51% |
17.51% |
| Acetic anhydride prices |
108-24-7 |
7,240 |
0% |
0.54% |
9.86% |
| Acetone prices |
67-64-1 |
8,363 |
-1.61% |
-0.79% |
0.32% |
| Ammonium nitrate prices |
6484-52-2 |
4,150 |
0% |
0% |
0% |
| Ammonium sulfate prices |
7783-20-2 |
1,240 |
-0.8% |
-3.69% |
5.24% |
| Aniline prices |
62-53-3 |
16,100 |
1.26% |
5.18% |
11.5% |
| Benzene prices |
71-43-2 |
10,441 |
-1.2% |
1.27% |
9.44% |
| Borax prices |
1303-96-4 |
6,740 |
0% |
2.13% |
4.75% |
| boric acid prices |
10043-35-3 |
11,600 |
0% |
0% |
0.47% |
| Butane prices |
106-97-8 |
6,700 |
0% |
0% |
0.25% |
| calcium carbide prices |
75-20-7 |
2,560 |
-0.78% |
-3.29% |
-0.64% |
| Calcium chloride prices |
10043-52-4 |
1,433 |
0% |
1.42% |
5.81% |
| Calcium phosphate prices |
7758-87-4 |
10,000 |
0% |
0% |
0% |
| Caustic Soda prices |
68988-74-9 |
631 |
0% |
-0.32% |
-0.78% |
| Chloroform prices |
67-66-3 |
2,600 |
0% |
6.08% |
9.03% |
| Cobalt prices |
7440-48-4 |
248,800 |
-2.12% |
-3.31% |
-9.1% |
| Dichloromethane prices |
75-09-2 |
3,295 |
0% |
18.53% |
26.49% |
| Dysprosium prices |
7429-91-6 |
1,955,000 |
0% |
0% |
-0.26% |
| Ethanol prices |
64-17-5 |
5,636 |
0% |
0.32% |
1.15% |
| ethyl acetate prices |
141-78-6 |
7,127 |
-1.01% |
5.08% |
10.01% |
| Ethylene glycol prices |
107-21-1 |
5,967 |
0% |
-5.22% |
-4.37% |
| Ethylene Oxide prices |
75-21-8 |
9,700 |
0% |
0% |
7.93% |
| EVA prices |
- |
11,467 |
0% |
3.5% |
3.71% |
| Formaldehyde prices |
50-00-0 |
1,853 |
-1.7% |
2.65% |
10.11% |
| Formic acid prices |
64-18-6 |
2,100 |
0% |
2.79% |
-9.11% |
| Heptane prices |
142-82-5 |
16,400 |
0.24% |
1.17% |
4.37% |
| Hexane prices |
110-54-3 |
10,325 |
0% |
0% |
5.43% |
| Hydrochloric acid prices |
7647-01-0 |
192 |
0% |
0.52% |
4.37% |
| Hydrogen peroxide prices |
7722-84-1 |
713 |
0% |
0% |
3.18% |
| Iodine prices |
7553-56-2 |
640 |
0% |
0% |
0% |
| Iron prices |
7439-89-6 |
6,000 |
0% |
0% |
5.63% |
| Lithium carbonate prices |
554-13-2 |
101,000 |
-2.88% |
-12.65% |
-15.52% |
| Magnesium chloride prices |
7786-30-3 |
880 |
0% |
0% |
0% |
| Methanol prices |
67-56-1 |
3,967 |
-0.58% |
-14.46% |
12.14% |
| Mineral oil prices |
8042-47-5 |
40,750 |
0% |
5.65% |
-24.09% |
| Nickel prices |
7440-02-0 |
117,383 |
-1.43% |
-3.37% |
-4.46% |
| PET prices |
- |
8,851 |
-0.12% |
-0.22% |
3.58% |
| Phenol prices |
108-95-2 |
9,413 |
-1.43% |
2.87% |
3.86% |
| Phosphoric Acid prices |
7664-38-2 |
8,400 |
0% |
0.21% |
-0.13% |
| Poly(vinyl alcohol) prices |
9002-89-5 |
10,400 |
0% |
0% |
0% |
| Potassium carbonate prices |
584-08-7 |
7,450 |
0% |
0% |
-0.63% |
| Potassium chloride prices |
7447-40-7 |
3,233 |
-0.52% |
-2.28% |
-0.93% |
| Potassium nitrate prices |
7757-79-1 |
4,588 |
0% |
-1.18% |
-1.91% |
| Propane prices |
74-98-6 |
6,150 |
0% |
0% |
0.36% |
| Propylene prices |
115-07-1 |
10,684 |
-0.16% |
6.29% |
6.58% |
| Propylene glycol prices |
57-55-6 |
9,317 |
-3.62% |
1.42% |
0.02% |
| PX prices |
- |
10,500 |
0% |
4.26% |
7.63% |
| Pyridine prices |
110-86-1 |
18,471 |
0% |
0% |
0.18% |
| Silicon prices |
7440-21-3 |
9,700 |
0% |
0.88% |
1.21% |
| Sodium bicarbonate prices |
144-55-8 |
1,208 |
0% |
0.58% |
0% |
| Sodium hydroxide prices |
1310-73-2 |
2,570 |
0% |
0.12% |
1.14% |
| Sodium sulfate prices |
7757-82-6 |
570 |
1.79% |
0.71% |
0.36% |
| Sulfur prices |
7704-34-9 |
6,652 |
-0.25% |
-8.83% |
-8.55% |
| sulfuric acid prices |
7664-93-9 |
1,558 |
0% |
-5.13% |
-6.93% |
| Titanium dioxide prices |
13463-67-7 |
14,260 |
0% |
0.24% |
0.53% |
| Toluene prices |
108-88-3 |
8,883 |
-0.94% |
1.44% |
7.04% |
| Urea prices |
57-13-6 |
1,728 |
-0.4% |
-2.25% |
-0.56% |
| White phosphorus prices |
12185-10-3 |
28,296 |
-0.35% |
1.89% |
0.69% |
| Xylene prices |
1330-20-7 |
8,693 |
-0.57% |
1.5% |
2.44% |
| Zinc chloride prices |
7646-85-7 |
11,825 |
0% |
0% |
0% |
| Zinc oxide prices |
1314-13-2 |
38,000 |
0% |
0% |
22.82% |
| Zinc sulfate prices |
7733-02-0 |
5,500 |
0% |
0% |
0% |
Basic chemicals saw
23 of 62 tracked products move — 3 higher against 20 lower, marginally milder than Friday’s 3-against-18 but the same direction, with 39 lines not moving at all. The three gains were
Aniline up 1.26% to CNY 16,100/ton,
Sodium sulfate up 1.79% to CNY 570/ton and
Heptane up 0.24% to CNY 16,400/ton. Everything else fell, led by
Propylene glycol down 3.62% to CNY 9,317/ton,
Lithium carbonate down 2.88% to CNY 101,000/ton,
Cobalt down 2.12% to CNY 248,800/ton,
Formaldehyde down 1.70% to CNY 1,853/ton,
Acetone down 1.61% to CNY 8,363/ton,
Phenol down 1.43% to CNY 9,413/ton,
Nickel down 1.43% to CNY 117,383/ton,
Benzene down 1.20% to CNY 10,441/ton,
ethyl acetate down 1.01% to CNY 7,127/ton,
Toluene down 0.94% to CNY 8,883/ton,
Ammonium sulfate down 0.80% to CNY 1,240/ton,
calcium carbide down 0.78% to CNY 2,560/ton,
Methanol down 0.58% to CNY 3,967/ton,
Xylene down 0.57% to CNY 8,693/ton,
Potassium chloride down 0.52% to CNY 3,233/ton,
Urea down 0.40% to CNY 1,728/ton,
White phosphorus down 0.35% to CNY 28,296/ton,
Sulfur down 0.25% to CNY 6,652/ton,
Propylene down 0.16% to CNY 10,684/ton and
PET down 0.12% to CNY 8,851/ton.
The sulphur chain stopped bleeding; the nitrogen chain did not. After Friday’s 7.15% capitulation,
sulfuric acid held exactly unchanged at CNY 1,558/ton — the industrial benchmark sat flat at CNY 1,557.50 — and
Sulfur gave back only 0.25% to CNY 6,652/ton, matching the benchmark reference to within a rounding error, though it remains 8.83% lower on the week. On the same board, liquid ammonia fell a further
4.27% to CNY 2,616.67/ton after Friday’s 6.29% collapse, taking its weekly loss to 12.97%, the worst of any chemical on the week table — the winter-demand failure is still being transmitted, now through the nitrogen leg. The downstream evidence is consistent:
Urea slipped 0.40% to CNY 1,728/ton (benchmark 1,727.50, weekly minus 1.71%),
Ammonium sulfate fell 0.80% to CNY 1,240/ton exactly matching the board’s weekly endpoint, and
Potassium chloride eased 0.52% to CNY 3,233/ton against the import benchmark’s 3,233.33. Monoammonium phosphate held at CNY 3,656.67/ton. The acid buyers have not returned; they have simply stopped marking the price down in panic, which is a different thing entirely.
Lithium’s repricing has broken the round number that anchored the whole complex. The tracked
Lithium carbonate line fell 2.88% to CNY 101,000/ton, its
thirteenth consecutive decline, a 24.6% loss from CNY 134,000/ton on September 22 in under four weeks, and the print matches the board’s battery-grade weekly endpoint of 101,000 exactly. The physical market is not the problem: September to November is the chain’s restocking window, full-chain inventory covers only 23.8 days and is forecast toward 14 by year-end, weekly output rose just 191 tonnes to 26,086 tonnes, spodumene CIF has eased to USD 1,350–1,380 and hydroxide prices are falling faster than carbonate (industrial minus 6.82%, battery grade minus 5.88% on the day, the board’s two worst chemicals). The futures market is trading past that reality: the Guangzhou exchange main contract closed at 96,320 yuan, down 4.20% at a new year-to-date low, an 18.88% weekly collapse, pricing a 2027–28 supply wave of roughly 500,000 tonnes of LCE a year against demand narratives that are fraying — NEV penetration near 67% means mathematically slower growth, and the 2027 storage view has turned openly bearish as project returns compress. The collateral damage is instructive: cathode maker Wanrun New Energy disclosed a hedging floating loss of CNY 93.85 million for September 29 to October 12 alone, and Anda Technology CNY 58.6 million to September 30 — long-biased industrial hedges that met a falling curve head-on. Outside lithium the metals picture split:
Cobalt fell 2.12% to CNY 248,800/ton for a fifth straight decline (minus 9.1% on the month) and
Nickel lost 1.43% to CNY 117,383/ton as the domestic contract dropped over 2%, but copper held (plus 0.03%) and tin actually rose 1.34% —
the retreat is now specific to the battery-metal complex while the base-metal benchmarks have settled. Within the segment,
Dysprosium at CNY 1,955,000/ton,
Silicon at CNY 9,700/ton and
Iron at CNY 6,000/ton were unchanged.
Aniline was the board’s one genuine cost-push gain, and it is a supply story. The line rose 1.26% to CNY 16,100/ton and the benchmark moved in perfect lockstep from CNY 15,900.00, putting aniline
101.38% above its year-earlier level and 5.18% higher on the week. The drivers are turnarounds and inventory position, not demand: Shanxi Tianqi began planned maintenance this week, Jilin Xuyang/Kan'er is next, and low East China port stocks plus mid-month short-covering lifted pure benzene, which lifts aniline — even though the tracked
Benzene line itself fell 1.20% to CNY 10,441/ton, and the board itself notes downstream acceptance is weakening at the new highs, which caps follow-through. The aromatic complex around it was green:
Ethyl acetate minus 1.01%,
Toluene minus 0.94%,
Xylene minus 0.57%,
PX unchanged at CNY 10,500/ton, and the domestic futures board printed declines over 1% in pure benzene, styrene (down 3.35% on the spot board), propylene, PP and bottle-grade flakes —
domestic chemical futures falling the same day crude gained 3.5% is the central divergence of the tape. The cumene pair confirms the demand read:
Phenol fell 1.43% to CNY 9,413/ton, retracing nearly all of Friday’s 1.60% gain, and
Acetone fell 1.61% to CNY 8,363/ton (benchmark CNY 8,362.50; still 102.97% year on year); both halves of the oxidation unit are now marked down together, so this is a uniform demand de-rating, not the previous session’s relative-value rotation. The coal-gas chain keeps unwinding its September squeeze:
Methanol minus 0.58% to CNY 3,967/ton (benchmark 3,966.67; weekly minus 14.46% against a monthly plus 12.14% that still leaves the level elevated),
Formaldehyde minus 1.70% to CNY 1,853/ton for a fourth consecutive decline (benchmark 1,852.50), and
Heptane eked a rare gain at plus 0.24% to CNY 16,400/ton, matched exactly by the board.
The flat list carries most of the segment’s weight:
Caustic Soda at CNY 631/ton (the futures contract fell 32 yuan to 1,740 as chlor-alkali utilisation dropped 4 points to 74.8% and integrated economics stayed negative),
Sodium hydroxide at CNY 2,570/ton,
Dichloromethane at CNY 3,295/ton holding a 18.53% weekly and 26.49% monthly gain — the biggest double winner on both clocks —
Chloroform flat at CNY 2,600/ton on a 6.08% weekly advance,
Formic acid flat at CNY 2,100/ton (minus 9.11% on the month),
Titanium dioxide at CNY 14,260/ton,
Phosphoric Acid at CNY 8,400/ton,
Ethylene glycol frozen at CNY 5,967/ton on a 5.22% weekly slide,
ethylene oxide at CNY 9,700/ton,
EVA at CNY 11,467/ton,
Butane at CNY 6,700/ton,
Propane at CNY 6,150/ton,
Borax,
boric acid,
Calcium chloride,
Calcium phosphate,
Ammonium nitrate,
Hydrochloric acid,
Hydrogen peroxide,
Sodium bicarbonate,
Sodium sulfate’s smaller cousins,
Pyridine,
Hexane,
Ethanol,
Iodine (CNY 640/kg),
Potassium carbonate,
Potassium nitrate,
Poly(vinyl alcohol),
Zinc chloride,
Zinc sulfate,
Zinc oxide at CNY 38,000/ton after a 22.82% monthly surge, and the returning artefact-prone line
Mineral oil flat at CNY 40,750/ton with its minus 24.09% monthly reading still carried on its back.
The overall read for Basic Chemicals is that
the correction phase has paused and a freeze has set in. Thirty-nine of 62 lines did not move; the panic items of Friday (sulphuric acid, sulfur) have found a floor for now; and the only genuine new price action is in the battery chain repricing 2027 and in a small cost-push pocket (aniline) that refuses to follow the crude surge. Energy costs are rising while chemical prices fall or sit still — that is a margin story, not a cost story, and it is why formaldehyde, melamine and acetone keep being marked down against a record oil tape. Buyers should treat the frozen lines as negotiation targets rather than panic items, watch whether the Hormuz premium finally breaks the chemical-side freeze, and note the two live exceptions: aniline at highs the board itself says downstream cannot digest, and PG unwinding back to its mid-September level within one session.
Fine Chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| Alkaline Phosphatase prices |
9001-78-9 |
20,000 |
0% |
0% |
0% |
| antifreeze prices |
- |
800 |
0% |
0% |
0% |
| Benzyl alcohol prices |
100-51-6 |
18,500 |
0% |
0% |
0.45% |
| calcium acetate prices |
62-54-4 |
6,800 |
0% |
0% |
-5.93% |
| Castor oil prices |
8001-79-4 |
15,000 |
0% |
2.88% |
2.55% |
| Citric acid prices |
77-92-9 |
6,200 |
0% |
0% |
0% |
| Clotrimazole prices |
23593-75-1 |
400,000 |
0% |
0% |
0% |
| dimethyl carbonate prices |
616-38-6 |
6,033 |
0% |
-0.71% |
-4.16% |
| Dimethyl sulfoxide prices |
67-68-5 |
12,075 |
0% |
4.06% |
4.32% |
| Ferric chloride prices |
7705-08-0 |
2,813 |
0% |
0.14% |
0.14% |
| glycolic acid prices |
79-14-1 |
13,000 |
0% |
0% |
0% |
| Guar gum prices |
9000-30-0 |
15,500 |
0% |
0% |
0% |
| Hydroquinone prices |
123-31-9 |
30,500 |
0% |
0% |
0% |
| Lactic acid prices |
50-21-5 |
8,288 |
0% |
1.31% |
1.07% |
| Magnesium glycinate prices |
14783-68-7 |
29,000 |
0% |
0% |
0% |
| Melamine prices |
108-78-1 |
6,250 |
-0.4% |
-0.9% |
0.77% |
| Melatonin prices |
73-31-4 |
850 |
0% |
0% |
0% |
| Oleic acid prices |
112-80-1 |
10,000 |
0% |
0% |
0% |
| Petroleum prices |
8009-03-8 |
9,300 |
0% |
0% |
0% |
| Potassium sorbate prices |
24634-61-5 |
15,100 |
-24.5% |
-11.08% |
2.87% |
| Quartz prices |
14808-60-7 |
6,800 |
0% |
0% |
0% |
| Retinol prices |
68-26-8 |
53 |
0% |
-3.64% |
-1.82% |
| Silver iodide prices |
7783-96-2 |
1,804 |
0% |
6.65% |
20.22% |
| sodium acetate prices |
127-09-3 |
5,643 |
0% |
1.48% |
1.83% |
| Sodium hypochlorite prices |
7681-52-9 |
553 |
0% |
0% |
0% |
| Sodium metabisulfite prices |
7681-57-4 |
3,893 |
0% |
-0.23% |
-1.14% |
| Tetrahydrofuran prices |
24979-97-3 |
19,500 |
-0.85% |
-2.95% |
9.61% |
| tranexamic acid prices |
1197-18-8 |
330 |
0% |
0% |
0% |
| Triclopyr prices |
55335-06-3 |
47,500 |
0% |
0% |
0% |
| Water softener salt prices |
- |
967 |
0% |
0% |
0% |
| Xanthan gum prices |
11138-66-2 |
21,000 |
0% |
0% |
0% |
Fine chemicals tracked
31 products, the segment’s widest coverage of the week after returning lines, and only
3 lines moved, all lower.
Melamine eased 0.40% to CNY 6,250/ton,
PTMEG (carried under the legacy English label Tetrahydrofuran) slipped 0.85% to CNY 19,500/ton, and
Potassium sorbate printed the artefact 24.5% decline. The other twenty-eight products were unchanged:
Alkaline Phosphatase,
antifreeze,
Benzyl alcohol,
calcium acetate,
Castor oil,
Citric acid,
Clotrimazole,
dimethyl carbonate,
Dimethyl sulfoxide,
Ferric chloride,
glycolic acid,
Guar gum,
Hydroquinone,
Lactic acid,
Magnesium glycinate,
Melatonin,
Oleic acid,
Petroleum,
Quartz,
Retinol,
Silver iodide,
sodium acetate,
Sodium hypochlorite,
Sodium metabisulfite,
tranexamic acid,
Triclopyr,
Water softener salt and
Xanthan gum — including all four CNY-per-kilogram lines, which sat perfectly still.
Potassium sorbate deserves the cleanest possible explanation because it is the headline number of the day and one of the two artefacts. On October 15 the line was quoted at CNY 20,000/ton, roughly 18% above its October 9 level of about CNY 16,980; today’s CNY 15,100/ton unwinds that outlier quote and then drifts below the week-ago level, leaving the true weekly reading at minus 11.08% and the month at plus 2.87%. The correct interpretation is
a bad print corrected, not a new collapse — and this edition therefore excludes it from every ranking and headline.
Anthracite, in the energy segment, has the identical structure: the October 15 quote of CNY 1,750/ton was about 9% above the week’s level, and today’s CNY 1,575/ton is where the market has actually been trading, only 1.87% below October 9.
Melamine eased 0.40% to CNY 6,250/ton, moving in exact lockstep with its urea feedstock (minus 0.40% on the same session, benchmark CNY 1,727.50) inside a nitrogen complex still running at historic-high operating rates with producer stocks near 1.48 million tonnes; on the month melamine is still 0.77% higher, so this is a grind, not a break.
PTMEG returned to coverage and immediately drifted lower, minus 0.85% to CNY 19,500/ton, retracing the September squeeze that left it 9.61% above month-start while the weekly reading turned 2.95% negative — spandex-chain offtake has not confirmed the earlier run-up, and given this line’s history of erratic prints its trend read should be taken with the usual caution. The quiet positive is
Sodium metabisulfite, unchanged at CNY 3,893/ton after Friday’s 0.18% slip: with sulfur down only 0.25% today, the feedstock-cost collapse flagged yesterday has itself stopped moving, and the pass-through pressure has paused with it.
dimethyl carbonate held at CNY 6,033/ton,
Dimethyl sulfoxide at CNY 12,075/ton on a 4.06% weekly advance,
Benzyl alcohol,
Lactic acid,
sodium acetate,
Castor oil (returned, flat, plus 2.88% weekly) and
Silver iodide (returned, flat, plus 20.22% monthly, the most artefact-prone line in the series and notably still today) completed the quiet board.
The practical message for fine-chemicals buyers:
the specialty book is dormant and the only genuine repricing is downward and mild. Twenty-eight of 31 lines are frozen; melamine’s erosion follows urea; PTMEG retraces but is still above its month-start. The two actionable notes: first, potassium sorbate buyers should test the market aggressively — the corrected 15,100 level is 11% below October 9 and the true trajectory, stripped of the artefact, is quietly negative; second, metabisulfite’s freeze only lasts as long as the sulphur chain’s does — if sulfur renews its slide, the pass-through conversation restarts. Everything else is a hold.
Energy, Rubber, Plastic and other chemicals Prices
| Product |
CAS |
Price |
Daily |
Weekly |
Monthly |
| ABS prices |
- |
12,007 |
-0.55% |
4% |
3.87% |
| Anthracite prices |
8029-10-5 |
1,575 |
-10% |
-1.87% |
0.83% |
| Asphalt prices |
8052-42-4 |
6,100 |
-0.7% |
-2.3% |
6.98% |
| Carbon prices |
7440-44-0 |
12,500 |
0% |
0.15% |
0.71% |
| Carbon Black prices |
1333-86-4 |
10,807 |
0% |
-6.49% |
0.57% |
| Gasoline prices |
- |
9,967 |
-0.35% |
-1.7% |
0.72% |
| HDPE prices |
- |
11,050 |
-0.67% |
4.69% |
-0.44% |
| kerosene prices |
- |
8,600 |
1.18% |
3.9% |
2.33% |
| Lead prices |
7439-92-1 |
16,180 |
-0.12% |
0.31% |
0.14% |
| Polyvinyl chloride prices |
93050-82-9 |
5,040 |
3.49% |
-5.76% |
-1.37% |
| PVC prices |
- |
4,780 |
0% |
-1.38% |
1.22% |
| Silica prices |
10279-57-9 |
6,367 |
0% |
-0.3% |
2.76% |
| WTI Crude Oil prices |
- |
98 |
3.16% |
6.67% |
-3.16% |
Energy, Rubber, Plastic and other chemicals tracked
13 products, of which
9 moved — 3 higher against 6 lower.
Polyvinyl chloride surged 3.49% to CNY 5,040/ton,
WTI Crude Oil gained 3.16% to USD 98/barrel and
kerosene added 1.18% to CNY 8,600/ton, while
Asphalt eased 0.70% to CNY 6,100/ton,
HDPE fell 0.67% to CNY 11,050/ton,
ABS slipped 0.55% to CNY 12,007/ton,
Gasoline dipped 0.35% to CNY 9,967/ton,
Lead lost 0.12% to CNY 16,180/ton and
Anthracite printed the artefact 10.0% decline to CNY 1,575/ton.
Carbon at CNY 12,500/ton,
Carbon Black at CNY 10,807/ton,
Silica at CNY 6,367/ton and the plain
PVC line at CNY 4,780/ton were unchanged.
Crude is the segment and the session (see the mover card above), so the worth-flagging item is the
divergence of every domestic energy line from it:
Gasoline fell 0.35% because pump prices are set by the ten-working-day formula mechanism and still carry the earlier downward adjustment window;
kerosene rose 1.18% on jet-demand and export economics; and
Asphalt declined for a third consecutive session, minus 0.70% to CNY 6,100/ton, as road-construction season winds into the north.
Oil up, refined products down — that is refinery margin compression, not a pass-through signal, and it is the same squeeze the chemical intermediates are living through.
Anthracite, once its artefact base is stripped, shows a coal market going sideways into the winter supply campaign — the level near CNY 1,575–1,605 matches October 9, and domestic coking futures still fell over 1% on the day.
The polymer complex resumed its two-speed drift, with PVC the lone riser. Outside it, the board is flat-to-soft:
ABS gave back 0.55% from its mid-week extension yet remains 4.00% higher on the week,
HDPE slipped 0.67% to CNY 11,050/ton (weekly plus 4.69%) while domestic plastics, PP and bottle-grade contracts all fell over 1%, and the second PVC line held flat at CNY 4,780/ton — the clearest tell that Thursday’s carbide-cost argument (calcium carbide minus 0.78% today, Wuhai trade at CNY 2,450/ton, semi-coke stable at CNY 1,030/ton) has not reversed; the PVC rebound rests entirely on maintenance schedules, loss-making supply cuts and continued de-stocking holding. The rubber chain, which broke last week, stabilised:
Carbon Black unchanged at CNY 10,807/ton after a 6.49% weekly collapse,
Silica unchanged at CNY 6,367/ton, while the board’s natural rubber actually rebounded 0.57% to CNY 19,241.67/ton and SBR added 0.31%.
Lead edged 0.12% lower at CNY 16,180/ton and
Carbon (activated carbon) held at CNY 12,500/ton.
Overall, the tape reads as
three separate markets sharing one file. The energy complex is repricing higher on geopolitics that no chemical demand justified. The battery chain is repricing lower on 2027 supply mathematics that no physical present has confirmed. And in between, two-thirds of the tracked basket is frozen because neither side is willing to pay for conviction. For a week the direction has been the same:
the squeeze on intermediate margins is the trade — rising energy cost, falling or flat chemical prices. Buyers should treat the flat lines as negotiation targets rather than panic items, treat PVC’s supply-led rebound as fragile while carbide keeps falling, and watch one question above all: whether the Hormuz premium finally breaks the chemical-side freeze. If it does, the flat lines are where the next repricing starts; if it does not, the artefacts aside, this is a market storing energy for someone else’s move.
Data Source & Update Methodology
The above pricing data is compiled from multiple market channels including domestic ex-works quotations, distributor transaction references, port prices, and mainstream spot market assessments. Data was updated on
October 16, 2026, based on the latest available trading activity and real-time market feedback collected by GuideTrends analysts and industry participants.
All prices are for reference purposes only and may vary depending on region, transaction volume, specification, and contract terms.
Explore More Chemical Price Data
Access Real-Time Chemical Market Intelligence
For real-time price updates, historical trend analysis, and detailed market insights covering thousands of chemical products, visit the
GuideTrends Database .
Track chemical prices, compare product specifications, monitor supply chain movements, and identify sourcing opportunities with professional market intelligence tools designed for global chemical buyers and suppliers.


 EN
 Agricultural News
 Food News
 Industrial News
 Cosmetic News
 Pharmaceutical News
 Science News

 1YR

